
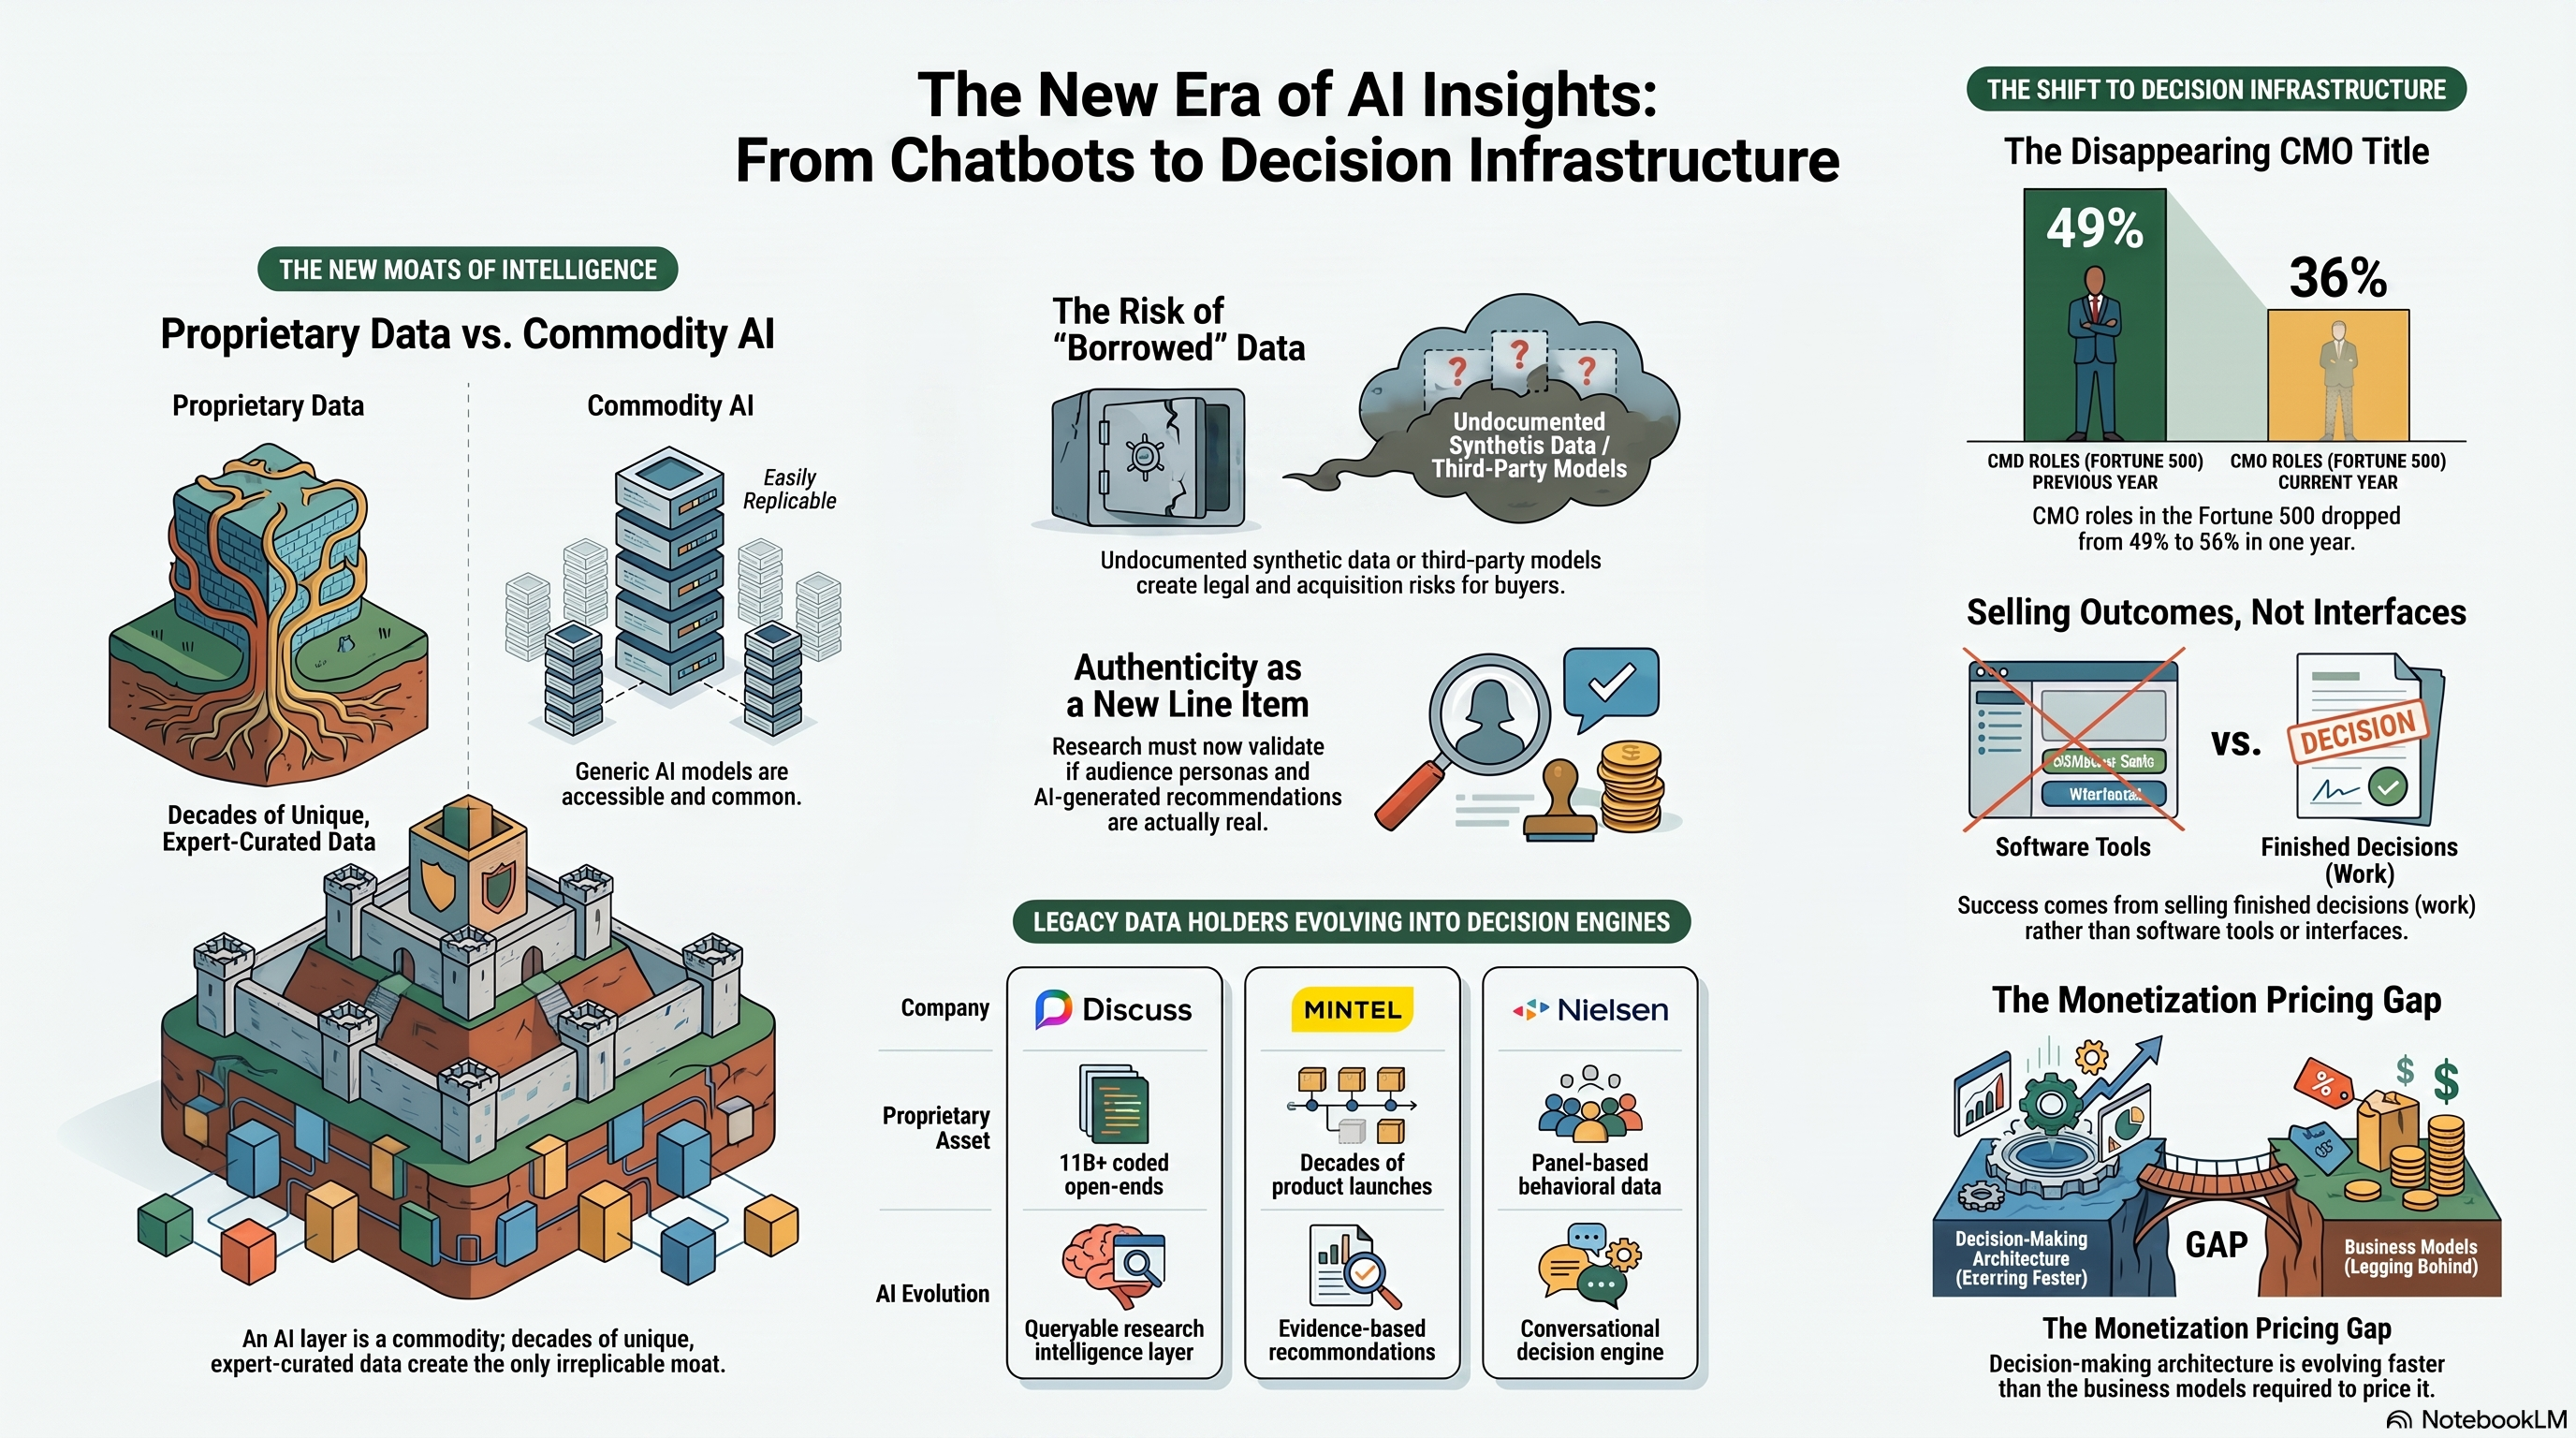
The industry keeps announcing “AI-native” products this week the way it announced “big data” products in 2013: as a category label, not a business model. But underneath the label rush, a real split is forming. Some of this week’s launches turn a research library, a panel, or a monitoring feed into something a client’s own AI systems can query and act on directly. Others just bolt a chat interface onto the same static deliverable and call it transformation. The products that survive the next eighteen months are the ones priced against the decisions they enable, not the seats or subscriptions they sell — which is exactly the problem we asked out loud this week: the architecture for decision infrastructure is coming together faster than anyone’s pricing model for it.
Meanwhile the sell side of the industry got a live case study in what happens to companies that never made that transition. Vertus Group, a division of serial acquirer Constellation Software, bought Welsh research-tech firm Delineate this week — a small, profitable, panel-adjacent business getting folded into a “buy and keep” software conglomerate’s portfolio. It plays out almost exactly like the exit thesis we also laid out on Wednesday: the multiple a supplier commands has almost nothing to do with its client roster and almost everything to do with whether it owns proprietary data and workflow-embedded technology, or is just renting access to both.
By the way, if you want to hear IIV Partner Lenny Murphy talk through a subset of this week’s news with Karen Lynch of Greenbook, he does a live webcast for Greenbook called The Exchange every Friday at 12pm ET — you can tune in here. This week’s stack of decision-infrastructure launches and supplier M&A gives us plenty to work with.
Research Goes From Library to Decision Infrastructure
Discuss has spent more than a decade coding over 11 billion open-ends, and it just turned that archive into a research intelligence layer that lets brand managers, product leaders, and marketing teams query an organization’s entire research library in plain language, with every answer traced back to the original participant, segment, and verbatim clip. A decade of shelved studies just became a live, queryable asset instead of a graveyard of PDFs, and the insights team no longer has to be the API between the archive and the question. That’s a bigger claim than “faster reporting.”
Rival Technologies Announces MCP and First Syndicated Intelligence Offering
Rival launched a Model Context Protocol connection that lets clients pull trusted human research directly into their own AI agents, and paired it with its first syndicated product, the Emerging Consumer Index, tracking Gen Z and Millennial spending power across the US and Canada. CEO Andrew Reid framed the MCP piece as letting insights teams work with their data “on their own terms” instead of building one-off integrations — the same open-standard logic Nielsen used this week for Ad Intel AI, and a second data point that MCP is becoming the default connective tissue between proprietary research data and the AI tools clients already run.
Mintel’s new capability inside its Global New Products Database replaces multiple manual searches and filters with direct, evidence-based recommendations grounded in the millions of product launches its analysts have tracked over decades. The company’s own framing draws the line explicitly: unlike a generic AI tool trained on public information, every recommendation traces back to a proprietary, expert-curated dataset that a competitor cannot simply scrape together.
NIQ Expands GenAI Capabilities Across gfknewron, Turning Trusted Intelligence Into Decisions Faster
NIQ added Smart Insights across its gfknewron platform this week, the same “trusted data plus AI reasoning” pitch nearly every legacy data holder is now making. The AI layer is increasingly table stakes; NIQ’s real advantage over a newer entrant is the decades of proprietary retail and consumer measurement sitting underneath it that a startup cannot replicate on any reasonable timeline.
STRAT7’s upgraded AI hub adds a more context-aware research assistant, direct quantitative analysis, and audio briefings, and it now “understands STRAT7’s agencies and capabilities” well enough to route work across the group’s seven divisions on its own. Nucleus is explicitly built, in COO Jonathan Clough’s words, to let consultants “spend more time interpreting the evidence” rather than doing the groundwork — a services firm using AI to protect the judgment layer while automating everything underneath it.
Throughline: Five different companies, five different starting assets, one identical move: turn a static archive or dashboard into something a client’s own AI can query and act on. The distinction that matters is not whether a company shipped an AI feature this week — nearly everyone did — but whether the underlying asset was proprietary and hard to replicate before the AI layer got added. Discuss’s decade of coded open-ends, Mintel’s decades of tracked launches, and NIQ’s retail measurement history are moats. A chat interface bolted onto a generic dashboard is not, and our pricing question raised earlier this week lands directly on that distinction: you can only charge for the decision if you actually own something that makes the decision better than the client could get elsewhere.
The Exit Thesis, Live
Acquisition for Welsh Success Story Delineate
Vertus Group, a division of Jonas Software within Constellation Software, has acquired UK-based research-tech and consumer opinion tracking firm Delineate. Delineate will keep operating independently from its Llandysul, Wales headquarters, but it now sits inside one of the largest “buy and keep” software conglomerates in the world, a strategy explicitly built to acquire and hold companies rather than roll them up and strip them down. It’s a profitable, proprietary-data company getting absorbed by a buyer whose entire model depends on finding exactly this kind of asset before someone else does, not a distressed sale.
Trooly is betting against the industry’s dominant AI-research instinct, which has mostly optimized for running more short, survey-like sessions faster. It is optimizing for depth instead: a single 45-minute AI-moderated interview, run at roughly 20x the speed and a tenth of the cost of a traditional one. Nearly $20 million in seed funding for a platform that deliberately does less, more slowly, than most of its AI-native competitors is a real bet that depth is the scarcer resource, not volume.
Further Funds for Marketing Data Platform PolyBox and Funds for Business Analytics Firm FireAI
Two much smaller raises the same week: UK-based PolyBox took in £700,000 to build out AI-driven analytics on top of its real-time market-data platform, and Mumbai-based FireAI raised roughly $260,000 for its causal decision-intelligence tool. Neither is a headline number. Both are early-stage bets on the same thesis Delineate just proved out at the acquisition stage — real-time, causal, or proprietary data infrastructure gets funded and eventually gets bought, even at very small scale.
Mayer Brown’s legal update is the diligence-side mirror of the Delineate deal: buyers of AI-heavy targets now need a full inventory of what proportion of a company’s training data is synthetic, whether that data is even copyrightable, and whether it was generated using a competitor’s model under terms that quietly forbid the use. Synthetic data that looks like a proprietary asset on the pitch deck can turn into undocumented legal exposure the moment a buyer’s counsel starts asking where it actually came from, and firms shopping a data moat built partly on synthetic generation should assume that question is coming.
Throughline: Delineate shows what a defensible small supplier looks like to a buyer with real capital. Trooly, PolyBox, and FireAI show investors betting on the same profile before it is provable. Mayer Brown shows the one place that thesis can quietly fall apart: a data asset that looks proprietary but was actually generated by a third-party model under terms nobody read. Own the data, know exactly how you made it, and be able to prove both — that is the entire operating agenda we laid out earlier this week, condensed into four stories that happened in the same seven days.
Who Validates What Shows Up in the Answer
Reach3’s new solution recreates specific audience personas and buying situations, then tests prompts against them repeatedly to find consistent patterns in how ChatGPT, Claude, Gemini, and other models recommend brands and products. Warner Bros. Discovery is already using it to understand how audiences discover entertainment content through AI. The premise is worth sitting with: because AI answers are probabilistic and personalized, the same question can return a different brand recommendation depending on who’s asking, which means “how do we rank in AI answers” is not a single number anyone can just look up. It has to be researched.
Interbrand’s Brand Strength framework, built for periodic assessment, is now embedded directly into Clootrack’s AI reasoning layer so every customer interaction, review, and support conversation gets scored against it continuously. A brand consultancy that built its business on the annual ranking report just turned its own methodology into an always-on monitoring product, a clear signal that the annual report format was never the actual asset. The framework was.
Cyabra’s new agent automates what its own human analysts used to do by hand: evaluate eight signals of coordinated inauthentic behavior and return one of four verdicts in under 30 seconds. It follows Cyabra’s partnership with Onclusive earlier this month, which put that same authenticity layer inside a media intelligence workflow used by communications teams. Cyabra is selling the analyst’s judgment, packaged into a defensible verdict, not the underlying detection signals — the same move Discuss made with its research archive and Mintel made with its product database, applied to trust instead of decisions.
Throughline: Three companies this week answered the same underlying question from three different angles: before you can trust what an audience thinks about a brand, you now have to validate that the audience, the conversation, or the AI recommendation itself is real. Reach3 is measuring how AI recommends brands. Interbrand and Clootrack are monitoring brand strength continuously instead of annually. Cyabra is verifying whether the conversation being measured was ever human to begin with. Layer these together and the research function’s job is quietly expanding: not just “what do people think,” but “is what I’m measuring even a real signal.”
Media Measurement Keeps Absorbing Agentic AI
Nielsen Ad Intel AI Launch Heralds Major Shift
Nielsen’s upgraded ad spend service moves from a reporting tool to what it calls a real-time conversational decision engine, accessible via Model Context Protocol so a client’s own AI agents can query it directly. CPO Akhil Parekh’s line is the whole pitch in one sentence: “The AI race relies on the most accurate data and that’s what Nielsen owns.” The AI layer is the least defensible part of this launch. The decades of panel-based behavioral data underneath it is the entire reason Nielsen can make this move and a challenger can’t.
Cint Expands Partnership with Samba to Bring Brand Lift Measurement to More International Markets and Dailymotion Launches Viewing Data Service
Cint extended its Samba integration to six more countries, letting advertisers measure TV brand lift in-flight instead of after the fact. Dailymotion’s new Pulse platform does the same thing for its own first-party viewing data across CTV, desktop, and mobile. Both are proprietary viewership signal getting turned into a real-time optimization loop rather than a post-campaign report, which is the ad-measurement version of the exact shift research platforms made this week.
StackAdapt Unveils New AI-First Ad Hub ‘Ivy Studio’ and Dstillery and Canvas Worldwide Partner to Bring DS-1 Agentic Optimization to Live Campaigns
StackAdapt’s new AI hub lets marketers describe outcomes in plain language instead of learning software workflows, with agents handling planning, forecasting, and execution — a week after the company added a dedicated political-advertising measurement suite. Dstillery went further and put agentic optimization into a live programmatic campaign with Canvas Worldwide, continuously surfacing what’s working instead of waiting for a weekly report, while explicitly keeping traders in control of every recommendation. Both companies are careful to frame this as augmentation, not replacement, but the work being augmented is optimization itself, which used to be one of the most billable-hours-heavy parts of a trader’s job.
Throughline: Ad-tech and media measurement are running the identical playbook as the research platforms above, just with a faster feedback loop: proprietary signal, plus an agent that can act on it continuously instead of quarterly. The through-line across both categories this week is that the AI layer is becoming a commodity feature almost everyone will ship. What differentiates the winners is what proprietary signal that layer sits on top of, and whether the company controlling that signal lets clients plug their own agents into it or insists on staying the only interface.
Who Does the Work, and Who Gets Credit for the Decision
The Fortune 500 Is Deleting the CMO Title
Forrester’s new analysis puts the CMO title at just 36% of Fortune 500 companies, down from 49% a year ago, with marketing executives sitting on the executive team or reporting to the CEO at 52%, down from 58%. The pattern across the companies that eliminated the role, UPS, Etsy, Walgreens, McDonald’s, Uber, and more, is that the function got absorbed into Chief Growth Officer, Chief Commercial Officer, or Chief Revenue Officer roles with direct ownership over revenue, not that marketing disappeared. For insights suppliers whose economic buyer used to be “the CMO,” that buyer is dissolving into people with finance instincts who want a case for lift tied to a P&L line, not a brand-tracking dashboard.
Building Expertise in the Age of AI: Who Trains the Next Generation?
McKinsey’s framing is that AI is hollowing out the routine work junior staff used to use to build judgment, and organizations that don’t deliberately redesign roles and embed learning will end up with senior people who never developed the pattern-recognition that used to come from doing the boring work themselves. Applied to insights teams that are automating fieldwork, coding, and first-pass analysis as fast as anyone: the junior researcher job that used to build the analyst who could later run point on a validated verdict is exactly the job getting automated away first.
Sequoia’s thesis, in a tweet that pulled 373,000 views this week: the next $1T company sells work, not software
The argument is that selling a copilot puts you in competition with every new model release, while selling the finished outcome, books closed, contracts reviewed, claims handled, means every model improvement widens your margin instead of threatening your product. It is the clearest one-line articulation yet of why Discuss, Mintel, and Cyabra all shipped verdicts and queryable assets this week instead of shipping better chat interfaces. Sell the software and the model vendor eventually eats your category. Sell the completed work and the model vendor’s progress becomes your cost structure improving underneath you.
Throughline: Three stories, one mechanism: the org chart is reorganizing around who owns the decision, not who owns the function that used to inform it. The CMO title is disappearing into revenue-owning roles. The junior researcher job that built future judgment is disappearing into automation. And the winning business model, per Sequoia, is the one that sells the finished decision rather than the tool that helps someone else make it. The market is stripping out every role and product that sits between the data and the decision without actually owning either one.
Interesting Reading
IPOs Test Investor Appetite for Unprofitable AI Giants — SpaceX’s $75 billion public debut, larger than every other US IPO combined over the past two years, is the first real test of whether public markets will keep funding AI companies burning billions with no near-term profitability, including xAI, which SpaceX acquired earlier this year.
Why Agencies Are Taking a Hybrid Approach to Synthetic Audience Research — Agencies are moving past treating synthetic audiences as an experiment and weaving them into client research programs, typically blended with real respondents rather than as a wholesale replacement.
How GenAI Can and Can’t Help Manage Customer Insights — MIT Sloan’s argument is that the bottleneck was never generating insights faster; it’s how customer knowledge actually flows through an organization once it exists, which GenAI does not automatically fix.
Our Position on Open-Weights Models — Dario Amodei says Anthropic has never advocated for banning open-weights models outright, and instead wants tighter chip controls on China, a crackdown on industrial-scale distillation, and mandatory safety testing applied to sufficiently capable models regardless of whether they’re open or closed.
Mira Murati Validates AI Model Commoditization and Control Layer Value — StJohn Deakins argues that Thinking Machines Lab’s results show the model layer commoditizing while value moves to the enterprise “control layer” sitting on top of it, evidenced by a fine-tuned open model beating frontier models on financial reasoning at a fraction of the cost.
Lighthouse or Landgrab? How to Pick Your AI Sales Strategy — a16z’s framing: buyers of AI products are purchasing either proof (a lighthouse customer who de-risks the category) or math (a landgrab economics case), and conflating the two sales motions is why a lot of AI go-to-market strategies stall out.
Big Idea of the Week
The insights industry didn’t get an AI upgrade this week. It got a pricing problem. Nearly every product launch above, Discuss’s queryable research archive, Rival’s syndicated MCP feed, Mintel’s deep research layer, Nielsen’s conversational ad intelligence, Cyabra’s automated verdict, is the same underlying move: take an asset that used to be sold as a project, a report, or a dashboard, and turn it into something that sits inside a client’s own decision workflow and gets queried continuously instead of delivered once. That is a genuinely different product, but in almost every case, not a genuinely different price.
We pointed at exactly this gap this week: the architecture for “decision as a service” is arriving faster than any coherent revenue model for it, and most companies are still pricing continuous decision infrastructure the way they priced a quarterly report, per seat, per license, per project, because that’s the only pricing model their finance teams and their clients’ procurement departments already understand. Meanwhile the exit market is already pricing the difference correctly: Delineate got bought by a buyer whose entire model is built on finding proprietary data that generates recurring value, at a multiple no report-based competitor without that asset base would command. The products are already ahead of the business models built to monetize them, and the acquirers already know it.
Implications for Suppliers
1. If your AI feature doesn’t sit on a proprietary asset, you shipped a chatbot, not a moat. Nearly every launch this week paired an AI layer with decades of proprietary data or research history: Mintel’s product launches, NIQ’s retail measurement, Nielsen’s viewing panels, Discuss’s coded open-ends. Audit what’s actually irreplicable underneath your AI feature before you market it as differentiated — if a competitor could rebuild it with an API key and a weekend, it isn’t.
2. The CMO buyer you built your case studies for may not exist at your next renewal. Fortune 500 marketing leadership is fragmenting into growth, commercial, and revenue titles with finance instincts, and the trend is accelerating, not stabilizing. Rebuild your value narrative around P&L-adjacent outcomes, revenue lift, retention, pipeline, not brand health metrics that only made sense to a buyer whose title is disappearing.
3. Decide now whether you’re selling software or selling the finished decision. Sequoia’s thesis says selling the outcome captures value as models improve; selling the interface loses value as models improve. Look at your product roadmap and ask honestly which side of that line each feature actually sits on, because the model vendors are not going to stop improving to make the answer more comfortable.
Implications for Buyers
1. The exit multiple gap between “owns proprietary data” and “rents panel access” just got a real-world price attached to it. Vertus/Constellation’s acquisition of Delineate is a live comp for exactly the asset profile we described this week. If you’re evaluating build-versus-buy for a data or workflow capability, use this deal as the reference point for what a buyer is actually willing to pay for, and price your own roadmap against it.
2. Your AI vendor’s synthetic data practices are now your acquisition diligence risk. Mayer Brown’s guidance makes clear that undocumented synthetic-data provenance can materially impair a deal’s value after signing, not just before. Ask every AI-native vendor you buy from for a synthetic-versus-licensed-versus-scraped data inventory now, before you’re doing it under deal-timeline pressure.
3. “Is this even a real signal” is becoming a line item, not a footnote. Cyabra, Interbrand/Clootrack, and Reach3 all launched products this week whose entire job is validating that what’s being measured is authentic before anyone measures what it means. Budget for authenticity and provenance verification as a distinct research line item, not something you assume your existing vendor already handles.
Implications for Investors
1. Buy-and-keep acquirers are running a systematic playbook on small proprietary-data suppliers, and there is more capital behind that thesis than most sellers realize. Constellation Software’s model is explicitly built to find and hold exactly the kind of asset Delineate represents. Track which small and mid-sized suppliers in your coverage universe fit that profile before a strategic buyer gets there first, because the pattern recognition required to spot the next Delineate is not complicated.
2. The SpaceX/xAI IPO is the real stress test for every AI-adjacent valuation in the sector. A $75 billion raise from a company still burning cash on AI ambitions is a direct read on whether public markets will keep funding pre-profitability AI bets at scale, which matters for every synthetic-data and AI-research company hoping to eventually exit at software multiples. Watch how this trades over the next two quarters as a leading indicator for appetite toward every other AI-native insights company eyeing a public exit.
3. Micro-raises like PolyBox and FireAI are cheap options on a thesis that just got validated at the acquisition stage. Neither company has scale yet, but both sit on the same proprietary-data-plus-causal-AI profile that just got bought out from under a category peer. Small checks into this profile right now are effectively buying the Delineate thesis at a fraction of what it will cost once more of these companies prove it out themselves.