
Over the last several months, a pattern has been getting harder to ignore.
A growing share of the most interesting activity around the insights, analytics, and market research industry is no longer being driven by venture logic alone. It is increasingly being shaped by a different kind of capital with a different kind of playbook: private equity.
That does not mean the industry is about to become a generic consolidation story. In fact, the opposite is true.
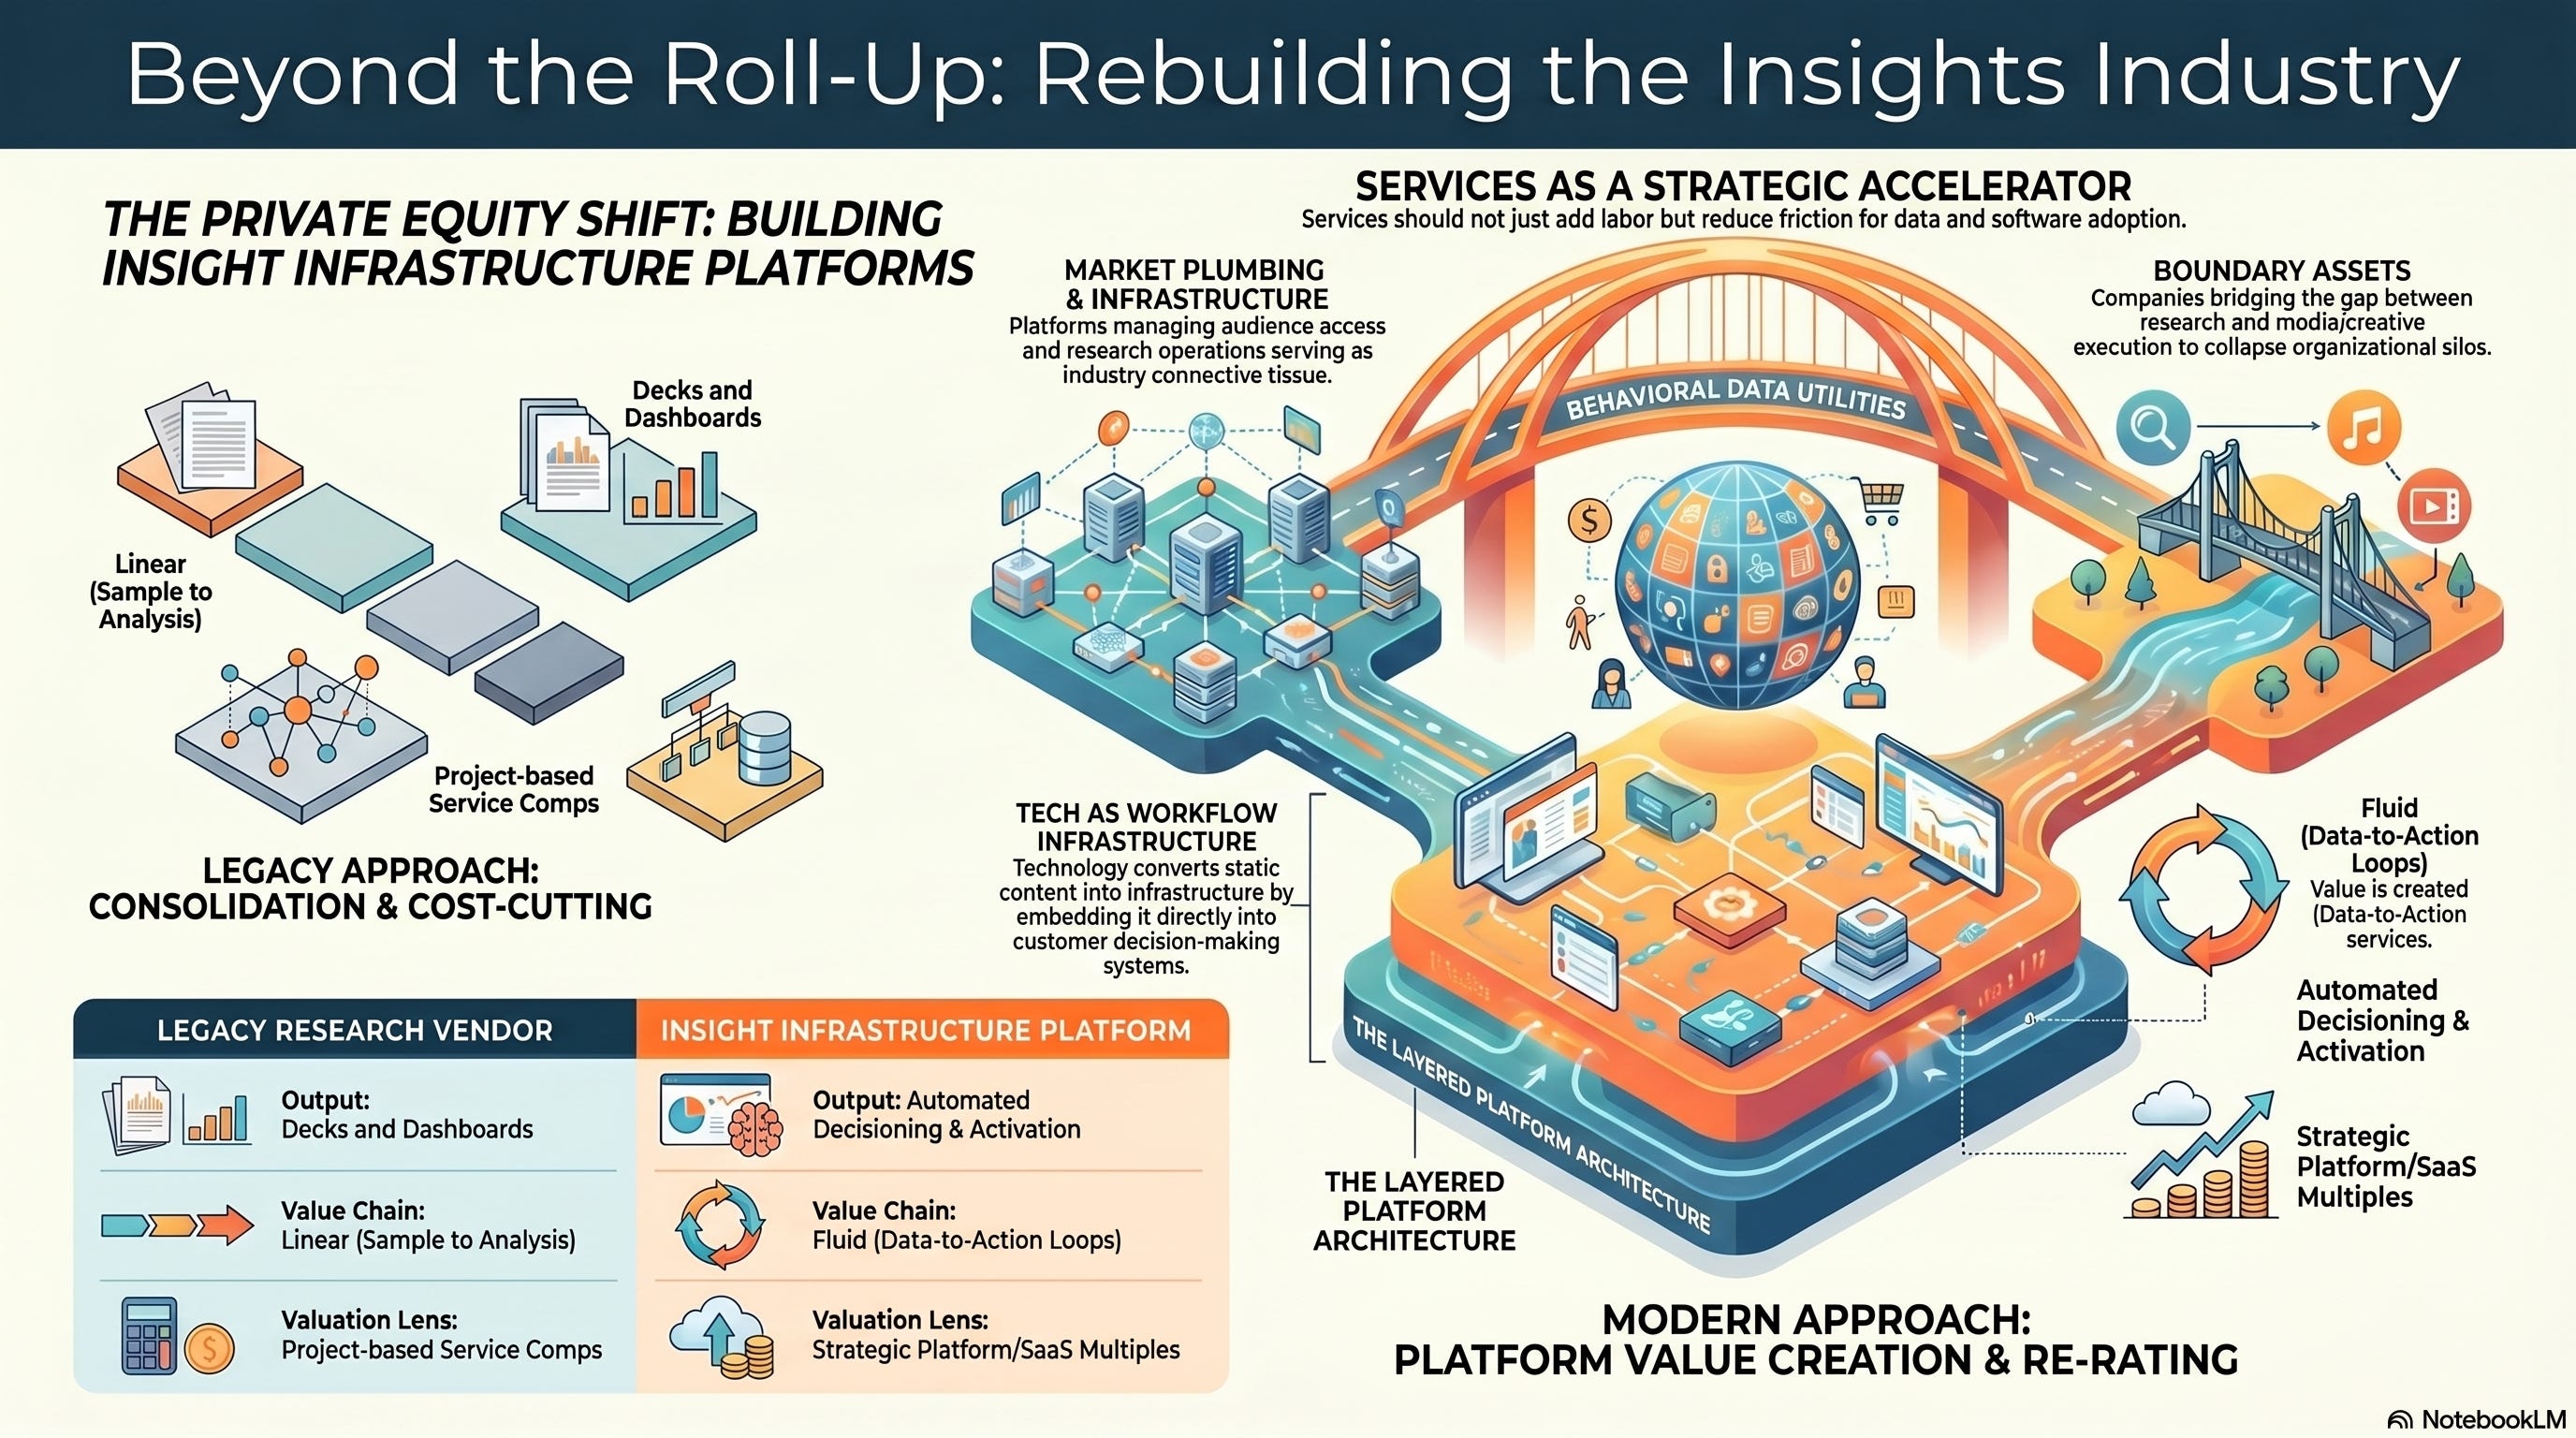
The old roll-up model of buy a handful of agencies, cut costs, call it scale is not the real opportunity here. The more important opportunity is taking assets that the market still sees as fragmented research businesses and rebuilding them into something much more valuable: insight infrastructure platforms.
That means platforms that combine some version of three layers:
proprietary or difficult-to-replicate data
workflow-embedded technology
value-accretive services that drive implementation, adoption, trust, and activation
The firms that understand this shift first will not just buy companies in the insights sector. They will change the category those companies belong to.
And that matters, because category changes are where valuation re-rating lives.
The category is being misread
One of the biggest mistakes investors still make in this industry is treating “market research” as if it were a stable category.
It is not.
What used to be a fairly linear value chain (sample, fieldwork, analysis, reporting) is collapsing into a more fluid system where data, intelligence, decisioning, and activation increasingly sit inside the same operating loop.
Survey data now gets blended with behavioral exhaust, transaction data, identity graphs, creative signals, and operational systems. Insight outputs are no longer just decks or dashboards; they increasingly feed segmentation, targeting, pricing, merchandising, media, and product workflows.
That shift changes what the best companies in the space actually are.
They are not just research providers. They are becoming pieces of enterprise decision infrastructure.
And once that happens, the relevant questions change too.
The right question is no longer: “How strong is this company’s position in the market research industry?”
The better question is: “Where does this company sit in the insight-to-activation value chain, and how essential could it become if rebuilt as infrastructure?”
That is the question more PE firms are beginning to ask, whether they use that language publicly or not.
Why private equity, and why now?
The macro backdrop matters here.
Across private equity, 2025 and 2026 have been defined by a few recurring themes: greater emphasis on operational value creation, selective aggression in tech and data-rich assets, a search for resilient recurring revenue, and strong interest in AI-adjacent infrastructure rather than AI theater. Sponsors are also under pressure to find assets where complexity can be converted into strategic clarity and margin expansion, not just financed with leverage.
That maps unusually well to the current state of the insights and analytics market.
This is an industry full of:
proprietary data assets with unclear packaging
subscale software with real workflow entrenchment
service-heavy companies hiding valuable IP
listed businesses still valued like niche vendors rather than strategic platforms
private companies hitting real scale but not yet framed as infrastructure
messy hybrid models sitting somewhere between research, martech, adtech, CX, and analytics
In other words, it is exactly the kind of environment where a hands-on PE firm can create value by re-architecting the asset, not just owning it.
Two PE plays are emerging
When this logic is applied to the sector, two complementary PE plays start to emerge.
1. Transforming legacy assets into aligned assets
The first play is to take legacy assets, either public or private, and reframe them around today’s strategic value pools.
That does not necessarily mean buying broken companies. It means buying companies whose market definition is out of date.
The classic version of this is a business with some mix of brand, proprietary data, embedded workflow, and services, but where the market still values it primarily as a research firm, project business, or low-growth information service.
These businesses often have stronger foundations than their current narrative suggests:
long-standing enterprise client relationships
recurring or quasi-recurring usage patterns
valuable first-party or permissioned data reservoirs
underexploited software layers that already sit in key workflows
underpriced adjacencies into segmentation, targeting, or activation use cases
too many products, brands, or delivery models obscuring the core asset
This is where PE can do some of its best work.
A sponsor can simplify the architecture, standardize the platform, rationalize the portfolio, invest in API and workflow layers, reshape the pricing model, and position the company around its most strategic control point.
The value creation is not just in cutting cost. It is in changing what the company is.
2. Creating new infrastructure from scaled private assets
The second play is to start with private or underappreciated scale assets that already occupy a meaningful control point in the value chain and help them mature into full infrastructure platforms.
These may be:
global panel and audience-access networks
sample exchanges and automated research-ops platforms
shopper and receipt-data utilities
tech-enabled full-service insight and CX operating platforms
In those cases, the PE role is less about rescue and more about completion.
The sponsor can provide the capital and operating discipline to:
consolidate adjacent capabilities like qual tech, communities, analytics, and activation
deepen product integration so the platform behaves like one system, not a toolkit
professionalize go-to-market around usage and platform economics
improve data governance and compliance to enterprise standards
sharpen the positioning from point solution to operating spine
create clearer strategic optionality for exit to software, media, or advisory buyers
This is especially relevant now because many companies in the sector are bumping into the same ceiling: they have scale, data, and clients, but not yet the product, architecture, or capital structure to become the obvious long-term winner in their layer of the stack.
The three-layer model matters more now
One of the most useful ways to think about PE opportunity in this space is through a three-layer lens: data + tech + services.
On their own, each layer is familiar. The key is what happens when they reinforce each other.
Data
The most attractive assets still begin with proprietary, permissioned, or operationally hard-to-replicate data. That can mean panels, receipt capture, consumer behavior, identity-linked audiences, brand tracking, public opinion, or longitudinal enterprise data.
But in the AI era, raw data ownership is not enough.
The data has to be usable, governable, refreshable, and capable of improving workflows over time. The firms that win are not just sitting on data reservoirs. They are building feedback loops around them.
Tech
Technology is what turns an asset from content into infrastructure.
The software layer matters because it determines whether the company is merely delivering information or actually embedding itself inside customer workflows. Workflow depth, APIs, automation, orchestration, integration, and self-serve interfaces all matter more than flashy feature sets.
This is the layer that creates stickiness, lowers delivery friction, and makes the asset more legible to strategic acquirers and infrastructure-minded financial buyers.
Services
This is the layer investors often misread.
In old frameworks, services were frequently seen as a valuation discount. Sometimes that is still true. But in this category, the right service layer can increase the strategic value of the asset when it helps clients implement, trust, customize, govern, and activate what the platform produces.
The point is not to maximize labor. The point is to use services to accelerate adoption and reduce friction around data and software.
That distinction matters. Bad services hide a weak product. Good services make a platform harder to dislodge.
The best PE targets are not “research companies”
Once that three-layer model is in view, a clearer set of target archetypes starts to emerge.
Mispriced listed data and IP assets
Some public companies in the space still trade inside frames that understate their strategic value.
They may be seen externally as survey businesses, niche ad-testing specialists, or information providers when in reality they own important combinations of proprietary data, strong brands, workflow entrenchment, and underdeveloped product potential.
From a PE lens, these are listed assets where:
the market still values them on legacy “research vendor” comps
a more modern narrative would place them closer to customer-intelligence or decision infrastructure
simplification and productization could unlock both growth and multiple expansion
Infrastructure hiding in plain sight
The cleanest opportunities may be the companies that function as market plumbing but are still discussed as suppliers.
Think about platforms that:
broker or manage access to audiences at scale
standardize how sample is bought, managed, and delivered
orchestrate research workflows across tools and vendors
sit quietly behind a large share of industry volume
These assets operate in the “rails” layer: they are the connective tissue of research operations rather than the visible brand at the front of a study. They behave more like infrastructure than like traditional services firms.
Other businesses in this archetype include global respondent and data-access backbones and tech-enabled fieldwork and CX platforms that can become more valuable if connected more tightly to downstream analytics and activation layers.
Shopper and behavioral data utilities
Another strong archetype is the shopper and behavioral data utility: businesses built around large-scale household or consumer panels, omnichannel purchase data, and high-frequency behavioral signals.
These platforms sit close to questions that matter deeply to enterprise buyers: pricing, assortment, retail media, promotion, brand performance, and category strategy. They often have:
rich longitudinal data at the household or individual level
strong relationships with major brands and retailers
embedded roles in planning and performance measurement cycles
From a PE perspective, these are forms of commercially proximate data infrastructure: assets where the line between “research” and “decisioning” is already thin.
Boundary assets between insight and activation
Then there is a final category: businesses that sit at the seam between insight, creative, media, and execution.
These companies often:
combine strategy, creative, data, and media capabilities
promise to “collapse silos” between research and activation
operate multiple brands or business units under one corporate umbrella
They are rarely attractive because they are clean. They are attractive because they contain the ingredients of the next platform category inside an overly complicated wrapper. For the right operator, that can be an invitation rather than a deterrent.
The most important trend is convergence
If there is one macro trend that sits underneath all of this, it is convergence.
The insights industry is no longer cleanly separate from adjacent categories such as martech, adtech, customer data infrastructure, retail media, and enterprise analytics. The best assets increasingly touch several of those categories at once, even if they came from a traditional research starting point.
That convergence shows up in a few ways.
First, the underlying data is becoming more blended. Survey responses alone are less differentiated than survey data combined with transactions, exposure, behavior, context, and identity resolution.
Second, the outputs are becoming more operational. Insight is increasingly expected to affect what a company does next, not just what it knows.
Third, the software layer is becoming more central. If a platform cannot connect into surrounding systems, it will struggle to become infrastructure no matter how good the data is.
And fourth, AI is accelerating the entire cycle. It increases the value of high-quality data, compresses delivery workflows, and raises the premium on assets that can become system-of-action tools instead of one-off answer engines.
This is exactly why PE attention is likely to rise.
Convergence creates ambiguity. Ambiguity creates mispricing. Mispricing is where smart capital gets interested.
What PE firms will likely screen for next
As this playbook develops, the screening criteria for attractive assets in the insights and analytics space will likely look different from the old list of top firms or largest agencies.
More likely, the best targets will share some combination of the following traits:
a defensible control point in the insight-to-activation chain
proprietary or operationally differentiated data foundations
software embedded enough in workflow to create switching costs
services that improve implementation and retention rather than simply adding labor
complexity that can be rationalized into a cleaner platform
room for category redefinition and multiple expansion
strategic relevance to buyers in software, data, media, consulting, or commerce
That is a much more demanding standard than simply being a solid business in market research.
But it is also a much more valuable one.
What this means for operators and founders
If this reading is directionally right, then the strategic implication for operators is straightforward: companies in this industry need to start telling the truth about what they are becoming.
For many, the answer is no longer “full-service insights firm” or “research technology provider.”
It is closer to:
customer intelligence infrastructure
audience decision platform
shopper and media signal utility
insight operating system
activation-ready research platform
Those are not just better taglines. They imply different product decisions, different M&A logic, different capital strategies, and different buyers.
The companies that prepare themselves for that future now will have more options later, whether the counterpart is VC, growth equity, PE, or a strategic acquirer.
That means doing the hard work before the market forces it:
simplifying product complexity
cleaning up data rights and governance
strengthening integration and API layers
clarifying where services add strategic value
aligning internal reporting around platform economics, not just project revenue
In other words, the next step for many companies in this industry is not just growth.
It is translation.
They need to translate themselves from legacy category definitions into the value frameworks that current capital markets actually reward.
The real opportunity is category conversion
This is why private equity may become more important to the future of the insights and analytics industry than many people currently expect.
Not because PE will simply consolidate a sleepy category.
But because PE is often most powerful when it recognizes that an asset is misnamed, misframed, or trapped inside an outdated market definition and then brings the capital, discipline, and operating pressure needed to turn it into what it should have been all along.
That is the opportunity here.
Some assets will be transformed from legacy businesses into aligned ones. Others will be created by stitching together scaled private capabilities into new infrastructure platforms. Some undervalued public companies may be taken private and rebuilt around more modern strategic logic. And entirely new AI-native utilities may emerge that deserve to be underwritten using a very different lens from the last generation of MR vendors.
The insights industry is not disappearing.
It is being reclassified.
The investors who understand that first will not just make better deals.
They will help define what the next version of the industry actually looks like.