
CB Insights recently published a report titled The Future of Professional Services: How firms will capture value in the AI agent era. The report is nominally about strategy consultancies, technology consultancies, and the Big Four, but the argument is much bigger than that. It is a map of what happens to any expertise business when AI agents begin absorbing routine work, clients get direct access to machine intelligence, and the old model of selling time, process, and outputs starts to break.
That includes market research.
Actually, it especially includes market research.
CB Insights identifies four priorities for professional services firms in the AI-agent era: orchestrate the AI agent tech stack, activate proprietary data for intelligent agents, turn services into scalable AI products, and build the human-AI workforce (CB Insights). Strip away the consulting-language wrapper and the message is blunt: firms that monetize advice, expertise, analysis, or implementation cannot survive by simply adding AI features to the same delivery model. They have to become systems businesses.
That is the exact transition now facing the insights industry.
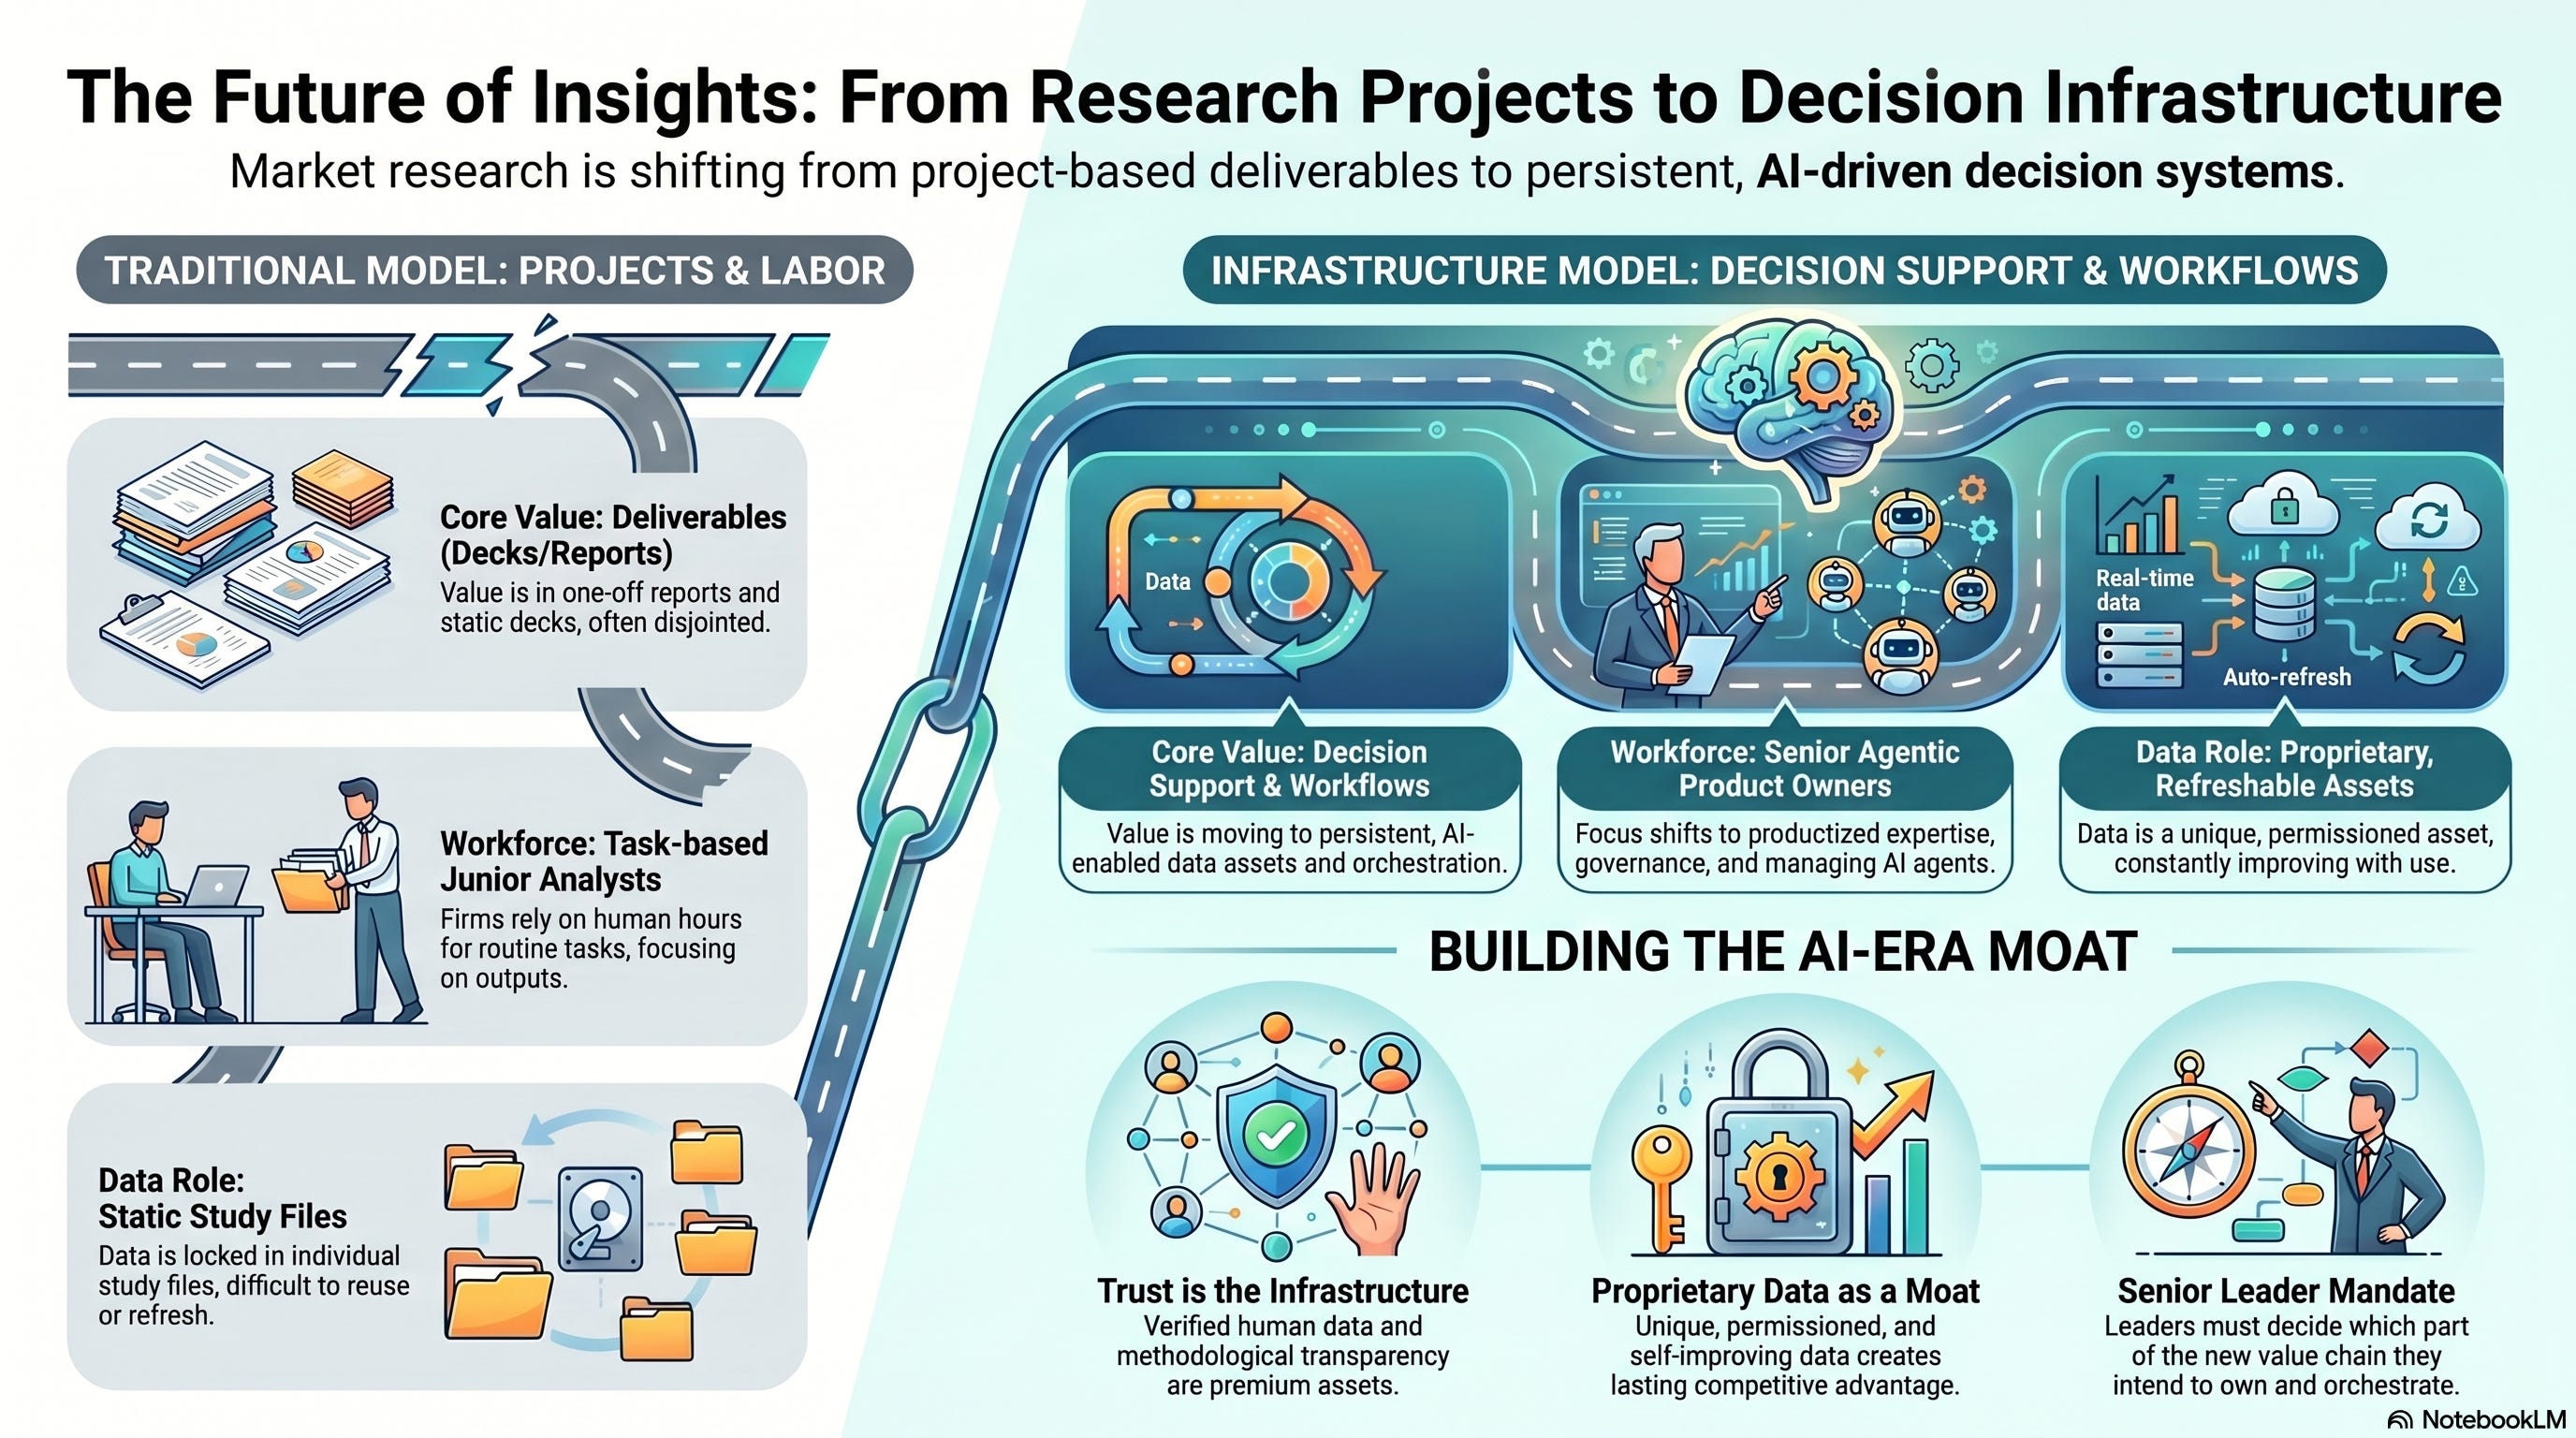
The old market research model was built around projects. A buyer had a business question. A supplier designed a study, collected data, analyzed it, produced a report, and maybe helped socialize the findings. The value was packaged as an output: a deck, a tracker, a segmentation, a brand study, a concept test, a qual report, a data table, a dashboard.
That model is not dead. But it is no longer structurally advantaged.
The new model is built around decision infrastructure. That means persistent data assets, AI-enabled workflows, embedded decision support, governance layers, quality controls, proprietary benchmarks, human judgment, and feedback loops that improve over time.
That is a different business.
CB Insights is describing a broader collapse of the labor-arbitrage model
The most important implication of the CB Insights report is not that Accenture, Deloitte, EY, KPMG, PwC, Bain, BCG, and McKinsey are all building AI strategies. Of course they are. The important point is that the economics of professional services are being attacked at the foundation.
CB Insights frames the central question this way: what happens to the traditional consulting model when clients have direct access to AI-powered expertise (CB Insights)?
That question should make every market research executive uncomfortable.
Because the same question applies here: what happens to the traditional research model when clients have direct access to AI-powered research design, analysis, synthesis, reporting, summarization, dashboarding, interviewing, coding, simulation, and decision support?
The easy answer is wrong. The easy answer is that AI automates tasks, so research firms should become more efficient. That is true, but it is far too small. Efficiency is the opening move, not the endgame.
The deeper issue is that AI changes where value accumulates.
When execution becomes cheaper, faster, and more automated, the premium shifts away from task completion. It moves toward problem specification, data legitimacy, workflow integration, governance, interpretation, and actionability. In other words, the value moves from producing research to operating the decision system around research.
That has been the central IIV thesis for some time: market research is being reclassified. It is no longer enough to think of the category as a supplier ecosystem that produces research outputs. The durable opportunity is to become part of the decision, data, workflow, and trust infrastructure of the enterprise.
CB Insights just made the same argument for professional services.
Orchestration is the new strategic center
CB Insights argues that professional services firms have an opening because enterprises are struggling to move beyond AI pilots. The blockers are familiar: integration complexity, security concerns, vendor sprawl, governance issues, and difficulty getting agentic systems into production (CB Insights).
That is not just a consulting problem. It is an insights problem.
Research buyers are about to face the same fragmentation. They will have AI survey builders, AI moderators, AI coding tools, AI transcription systems, synthetic respondent platforms, sample-quality systems, data-cleaning agents, knowledge-management agents, dashboard copilots, CRM intelligence tools, CX platforms, product analytics systems, and internal enterprise LLM environments. None of that automatically creates better decisions.
In many cases, it creates more noise.
The winner is not the firm with the most AI features. The winner is the firm that can orchestrate the system.
For MR suppliers, orchestration means connecting the entire insight-to-decision chain:
Problem framing.
Method selection.
Sample and data-source validation.
Survey or discussion-guide design.
Data collection.
Fraud detection and quality control.
Analysis and synthesis.
Human validation.
Stakeholder-specific storytelling.
Workflow delivery.
Decision activation.
Outcome feedback.
Most research firms only own pieces of this chain. Many are still organized around deliverables, not workflows. That is the vulnerability.
If a research supplier sits outside the client’s workflow, it can be replaced by something inside the workflow. If a supplier only delivers analysis, it can be compressed by an agent. If a supplier only sells access to respondents, it can be commoditized by marketplaces, synthetic data, or alternative data systems. If a supplier only sells dashboards, it can be absorbed into enterprise analytics and AI platforms.
Orchestration is how suppliers avoid becoming point solutions.
Proprietary data is not a slogan. It is the moat.
CB Insights puts heavy emphasis on proprietary data. The report argues that the most powerful agents will be grounded in high-quality proprietary data, and that professional services firms have an advantage because they have observed processes across thousands of companies (CB Insights).
That is exactly right. But in market research, the proprietary data question is even more important.
The insights industry has been sloppy with the phrase “data asset.” A file is not a data asset. A survey archive is not automatically a data asset. A panel is not automatically a moat. A tracker is not automatically a proprietary intelligence system.
A true AI-era data asset has several characteristics:
It is unique.
It is permissioned.
It is refreshable.
It is structured.
It has provenance.
It improves with use.
It can be activated inside a workflow.
It gives an agent context that a generic model cannot infer.
That definition raises the bar.
For sample and panel companies, the data moat is no longer just respondent access. It is verified identity, fraud signals, longitudinal respondent history, behavioral enrichment, consent architecture, and proof that the human on the other end is real.
For full-service research firms, the data moat is not just past decks sitting in SharePoint. It is coded category knowledge, decision taxonomies, benchmark databases, proprietary norms, methodological learnings, customer-language libraries, and structured insight corpora that can improve future work.
For research technology platforms, the data moat is not just usage logs. It is workflow telemetry, quality signals, research design patterns, question-performance data, respondent behavior, and integration context across the buyer’s decision systems.
For consultancies and advisory firms, the data moat is not just expertise. It is the ability to convert expert judgment into reusable systems, agents, playbooks, and governance frameworks.
The firms that do this will compound. The firms that do not will be stuck selling labor into a market where labor is being compressed.
The “full-service” label is becoming strategically weak
There is a version of full-service research that remains valuable. But the label itself is becoming less useful.
Historically, “full service” meant the supplier could manage the whole research project. That was valuable when complexity lived in execution: designing the study, programming the survey, finding respondents, fielding the work, cleaning data, analyzing findings, and preparing the report.
AI attacks that bundle.
Not all at once. Not perfectly. Not without errors. But directionally and structurally.
The more AI automates pieces of research execution, the less defensible “we can do the whole project for you” becomes as a standalone promise. Buyers will still need help, but the nature of that help changes. They will not pay premium fees for human beings to perform tasks that AI can perform adequately. They will pay for confidence, judgment, integration, governance, and outcomes.
So the better question is not whether full service survives. It is what full service becomes.
The answer is not “humans plus AI.” That is too vague. The answer is productized expertise.
Productized expertise means the supplier has converted its best human judgment into repeatable systems. It has reusable methodologies, proprietary data loops, workflow-specific agents, quality-control processes, benchmarks, templates, taxonomies, and activation playbooks. Humans still matter, but they are no longer the machinery. They are the supervisors, interpreters, validators, designers, and strategic translators.
That is a very different margin model.
It is also a very different talent model.
The research workforce has to be rebuilt, not merely trained
CB Insights argues that professional services firms are facing a workforce restructuring. The report says the traditional consulting pyramid is under pressure as AI handles routine work, pushing firms toward senior-heavy, specialized teams and workers who become “agentic product owners” rather than task executors (CB Insights).
This is one of the most important points for market research leaders.
The insights industry has its own version of the pyramid. It may not look exactly like McKinsey or Deloitte, but the same logic exists: junior researchers, analysts, project managers, survey programmers, data processors, moderators, report writers, and operations teams doing the work that supports senior client leadership and advisory roles.
AI will not eliminate all of those jobs. But it will change the economic logic behind them.
The junior researcher who can only summarize transcripts, clean data, make charts, draft toplines, or assemble slides is exposed. The project manager who only moves tasks through a process is exposed. The analyst who waits for instructions and produces descriptive findings is exposed.
The new premium profile is different:
Can this person specify the right business question?
Can they choose the right method?
Can they identify bad data?
Can they supervise AI workflows?
Can they challenge plausible but wrong outputs?
Can they explain uncertainty?
Can they connect findings to business action?
Can they influence stakeholders?
Can they design a decision process, not just a study?
That is not training. That is a talent-system redesign.
Most firms will underreact. They will buy AI tools, run internal training sessions, create prompt libraries, and declare progress. That will not be enough.
The actual work is harder: redesign roles, career paths, leverage models, pricing, hiring criteria, QA processes, knowledge management, and client delivery expectations around AI-native work.
Trust becomes infrastructure
CB Insights discusses the need for AI agent governance, observability, evaluation, and reliability. It notes that agents that hallucinate, fail, or behave unpredictably create immediate business risk, and it highlights growing deal activity around AI agent observability, evaluation, and governance (CB Insights).
This is where the market research industry should have a structural advantage, if it chooses to use it.
Research has always been in the trust business. The industry understands sampling, bias, representativeness, fraud, weighting, methodology, confidence, respondent quality, and interpretation risk. Or at least it should.
The problem is that the industry has often treated these capabilities as back-office hygiene rather than front-office strategic value.
That has to change.
In an AI-mediated insights world, trust is not a footnote. It is the product.
Buyers will need to know:
Was the respondent real?
Was the data permissioned?
Was synthetic data used?
Was the source disclosed?
Was the sample appropriate for the decision?
What was excluded?
Where did the model infer beyond evidence?
Which claims are grounded in observed human data?
Which claims are based on simulation?
Who validated the output?
What level of decision risk remains?
This is where MR can differentiate from generic AI.
A generic model can produce an answer. A research-grade system should produce a defensible answer.
That distinction matters.
Synthetic data is useful. Synthetic certainty is dangerous.
The CB Insights report mentions synthetic user generation as an emerging area in agent testing. That makes sense. Synthetic users can be valuable for simulation, QA, scenario planning, concept exploration, and agent evaluation.
But market research needs to be more disciplined here than the broader AI ecosystem.
Synthetic respondents are not magic. They are not a clean replacement for verified human beings. They are model outputs shaped by training data, assumptions, prompts, and system design. They can help generate hypotheses. They can test survey logic. They can simulate potential reactions. They can support early-stage ideation. They can reduce some cost and time in specific contexts.
But if a buyer needs to understand actual human attitudes, behaviors, tradeoffs, emotions, unmet needs, category context, or purchase drivers, then synthetic data has to be handled carefully.
The worst version of the future is not that synthetic data is used. It will be used. The worst version is that synthetic data is laundered into false confidence.
This is why verified human data may become more valuable, not less.
As synthetic content floods the system, proof of human becomes a premium asset. Provenance becomes a premium asset. Consent becomes a premium asset. Quality becomes a premium asset. Methodological transparency becomes a premium asset.
That is a major opportunity for the insights industry if it does not squander it.
Service-as-software is coming for research
CB Insights says professional services firms are moving from one-off project delivery toward scalable, product-like offerings powered by AI-agent platforms (CB Insights). It also points to experimentation with subscription, usage-based, hybrid, and outcome-based pricing models as AI changes service economics (CB Insights).
Market research should expect the same.
This does not mean every research firm becomes a SaaS company. That is the wrong lesson. Most research firms are not structurally equipped to become software companies, and pretending otherwise has destroyed plenty of value already.
The better frame is service-as-software.
That means taking the expertise, workflows, data, judgment, and repeatable methods inside a services business and packaging them into systems that scale better than labor alone.
Examples in insights could include:
Always-on category intelligence systems.
AI-assisted concept testing platforms with human validation.
Proprietary segmentation agents connected to client CRM data.
Research-design copilots trained on a firm’s best methods.
Synthetic pretesting environments clearly labeled as simulation.
Sample-quality scoring systems with provenance trails.
Brand-tracking agents that detect change and trigger human review.
Qualitative analysis systems that combine machine coding with expert interpretation.
Decision-risk scoring tools for executives.
Insight activation agents embedded into product, marketing, and innovation workflows.
The commercial model changes too.
Some revenue will remain project-based. Some will move to subscriptions. Some will move to retainers. Some will be usage-based. Some may include performance-linked components where attribution is clear enough. But the direction is obvious: the pricing model has to move closer to persistent value and farther away from hours consumed.
The senior-leader mandate
The CB Insights report should not be read as a technology forecast. It should be read as a management warning.
If you lead an insights company, the mandate is not “adopt AI.” That is table stakes.
The mandate is to decide where in the new value chain you intend to win.
There are several viable positions:
Own verified human data.
Own sample trust and provenance.
Own workflow orchestration.
Own a vertical decision system.
Own proprietary benchmarks.
Own AI research governance.
Own expert interpretation.
Own activation inside enterprise workflows.
Own a specialized data asset no one else can replicate.
What is not viable is staying in the mushy middle: generic research execution, generic dashboards, generic AI features, generic “full service,” generic panels, generic insights platforms, generic thought leadership.
Generic is where margin goes to die.
Senior leaders should be asking harder questions:
What do we know that a model does not?
What data do we have that competitors cannot replicate?
What workflow do we improve continuously?
What trust problem do we solve?
What decisions do we help clients make better?
What parts of our delivery model should become software-like?
What parts require human judgment and should be priced accordingly?
What roles disappear, what roles change, and what roles become more valuable?
Where are we still selling labor while pretending it is strategy?
Those questions are uncomfortable. Good. Comfortable questions produce incremental answers.
The real threat is not AI. It is abstraction.
The most dangerous thing that can happen to a research supplier is not that AI replaces it directly. The more likely danger is that the supplier gets abstracted.
The client’s enterprise AI platform abstracts the dashboard. The CX platform abstracts the survey. The CRM abstracts customer understanding. The product analytics platform abstracts user research. The consulting firm abstracts the insight layer into a transformation program. The sample marketplace abstracts respondent access. The synthetic data tool abstracts early-stage testing. The AI agent abstracts the analyst.
One layer at a time, the traditional supplier becomes less visible.
That is the real strategic threat.
To avoid it, MR firms have to move closer to where decisions happen. They have to embed into workflows, own trusted data, provide governance, and deliver judgment that cannot be reduced to automated output.
The future of market research is not a better report.
It is not a faster survey.
It is not an AI-generated dashboard.
It is trusted decision infrastructure.
CB Insights was writing about professional services. But the warning is ours too.
The firms that understand this will use AI to become more embedded, more valuable, and more scalable.
The firms that do not will use AI to make the old model a little faster right before the old model becomes structurally obsolete.
Glad to see verified human data as an essential asset. It also looks like restech companies need to have their services ready to be integrated into an automated system. For us that means not just having a self-service project launch website but an api connection.
For better or worse, it seems the market would eventually just be 3-4 big companies that own the full process plus some leaders in specific verticals. If you focus on a piece of the puzzle, it's just a question of when you agree to be acquired. That has interesting implications for funding.
The most interesting part will be setting decision rules because there isn't really much data now, as far as I know, to say, "the research said x, we decided to do y, and z happened." CRM data could work, I suppose, where it's granular enough. Any survey admin platforms currently integrated with Salesforce? Because that will seem to become the norm.
Excellent perspective on how AI is reshaping professional services. The future will likely belong to firms that combine AI-driven efficiency with uniquely human strengths such as strategic thinking, relationship building, ethical judgment, and industry expertise. While AI can automate analysis and routine tasks, clients will continue to value trusted advisors who can provide context, navigate uncertainty, and drive business outcomes. The most successful professional services organizations will be those that embrace AI as a force multiplier rather than viewing it as a replacement for human expertise.