
Note: We are experimenting with various ways to make our content more engaging and impactful using AI tools like Notebook LM. You’ll notice a variety of graphics in this report, but we also have adapted the content to a video as a “tldr” option. Let us know what you think of both?
Here is the video summary of the post first.
We’re continuing our deep dive into specific sectors of the insights & analytics market that we started in The Future of Professional Services Is a Warning Shot for Market Research, continued in The Data Infrastructure Layer Is Being Rebuilt — Is the Insights Industry Sleeping Through It?, and extended in Synthetic Sample Is Not the Market. Decision-Grade Data Is. — now turning to the self-serve research technology market.
Self-serve research technology was the disruption. The platforms that automated survey design, recruited respondents, and delivered toplines in hours — rather than the weeks it took traditional agencies — genuinely changed how brands make decisions. They won Wave 1. They reduced cost, compressed timelines, cut dependence on external agencies, and put research capacity directly into marketing, product, CX, and strategy teams. That was the bet, and it paid off.
Now the bet has changed.
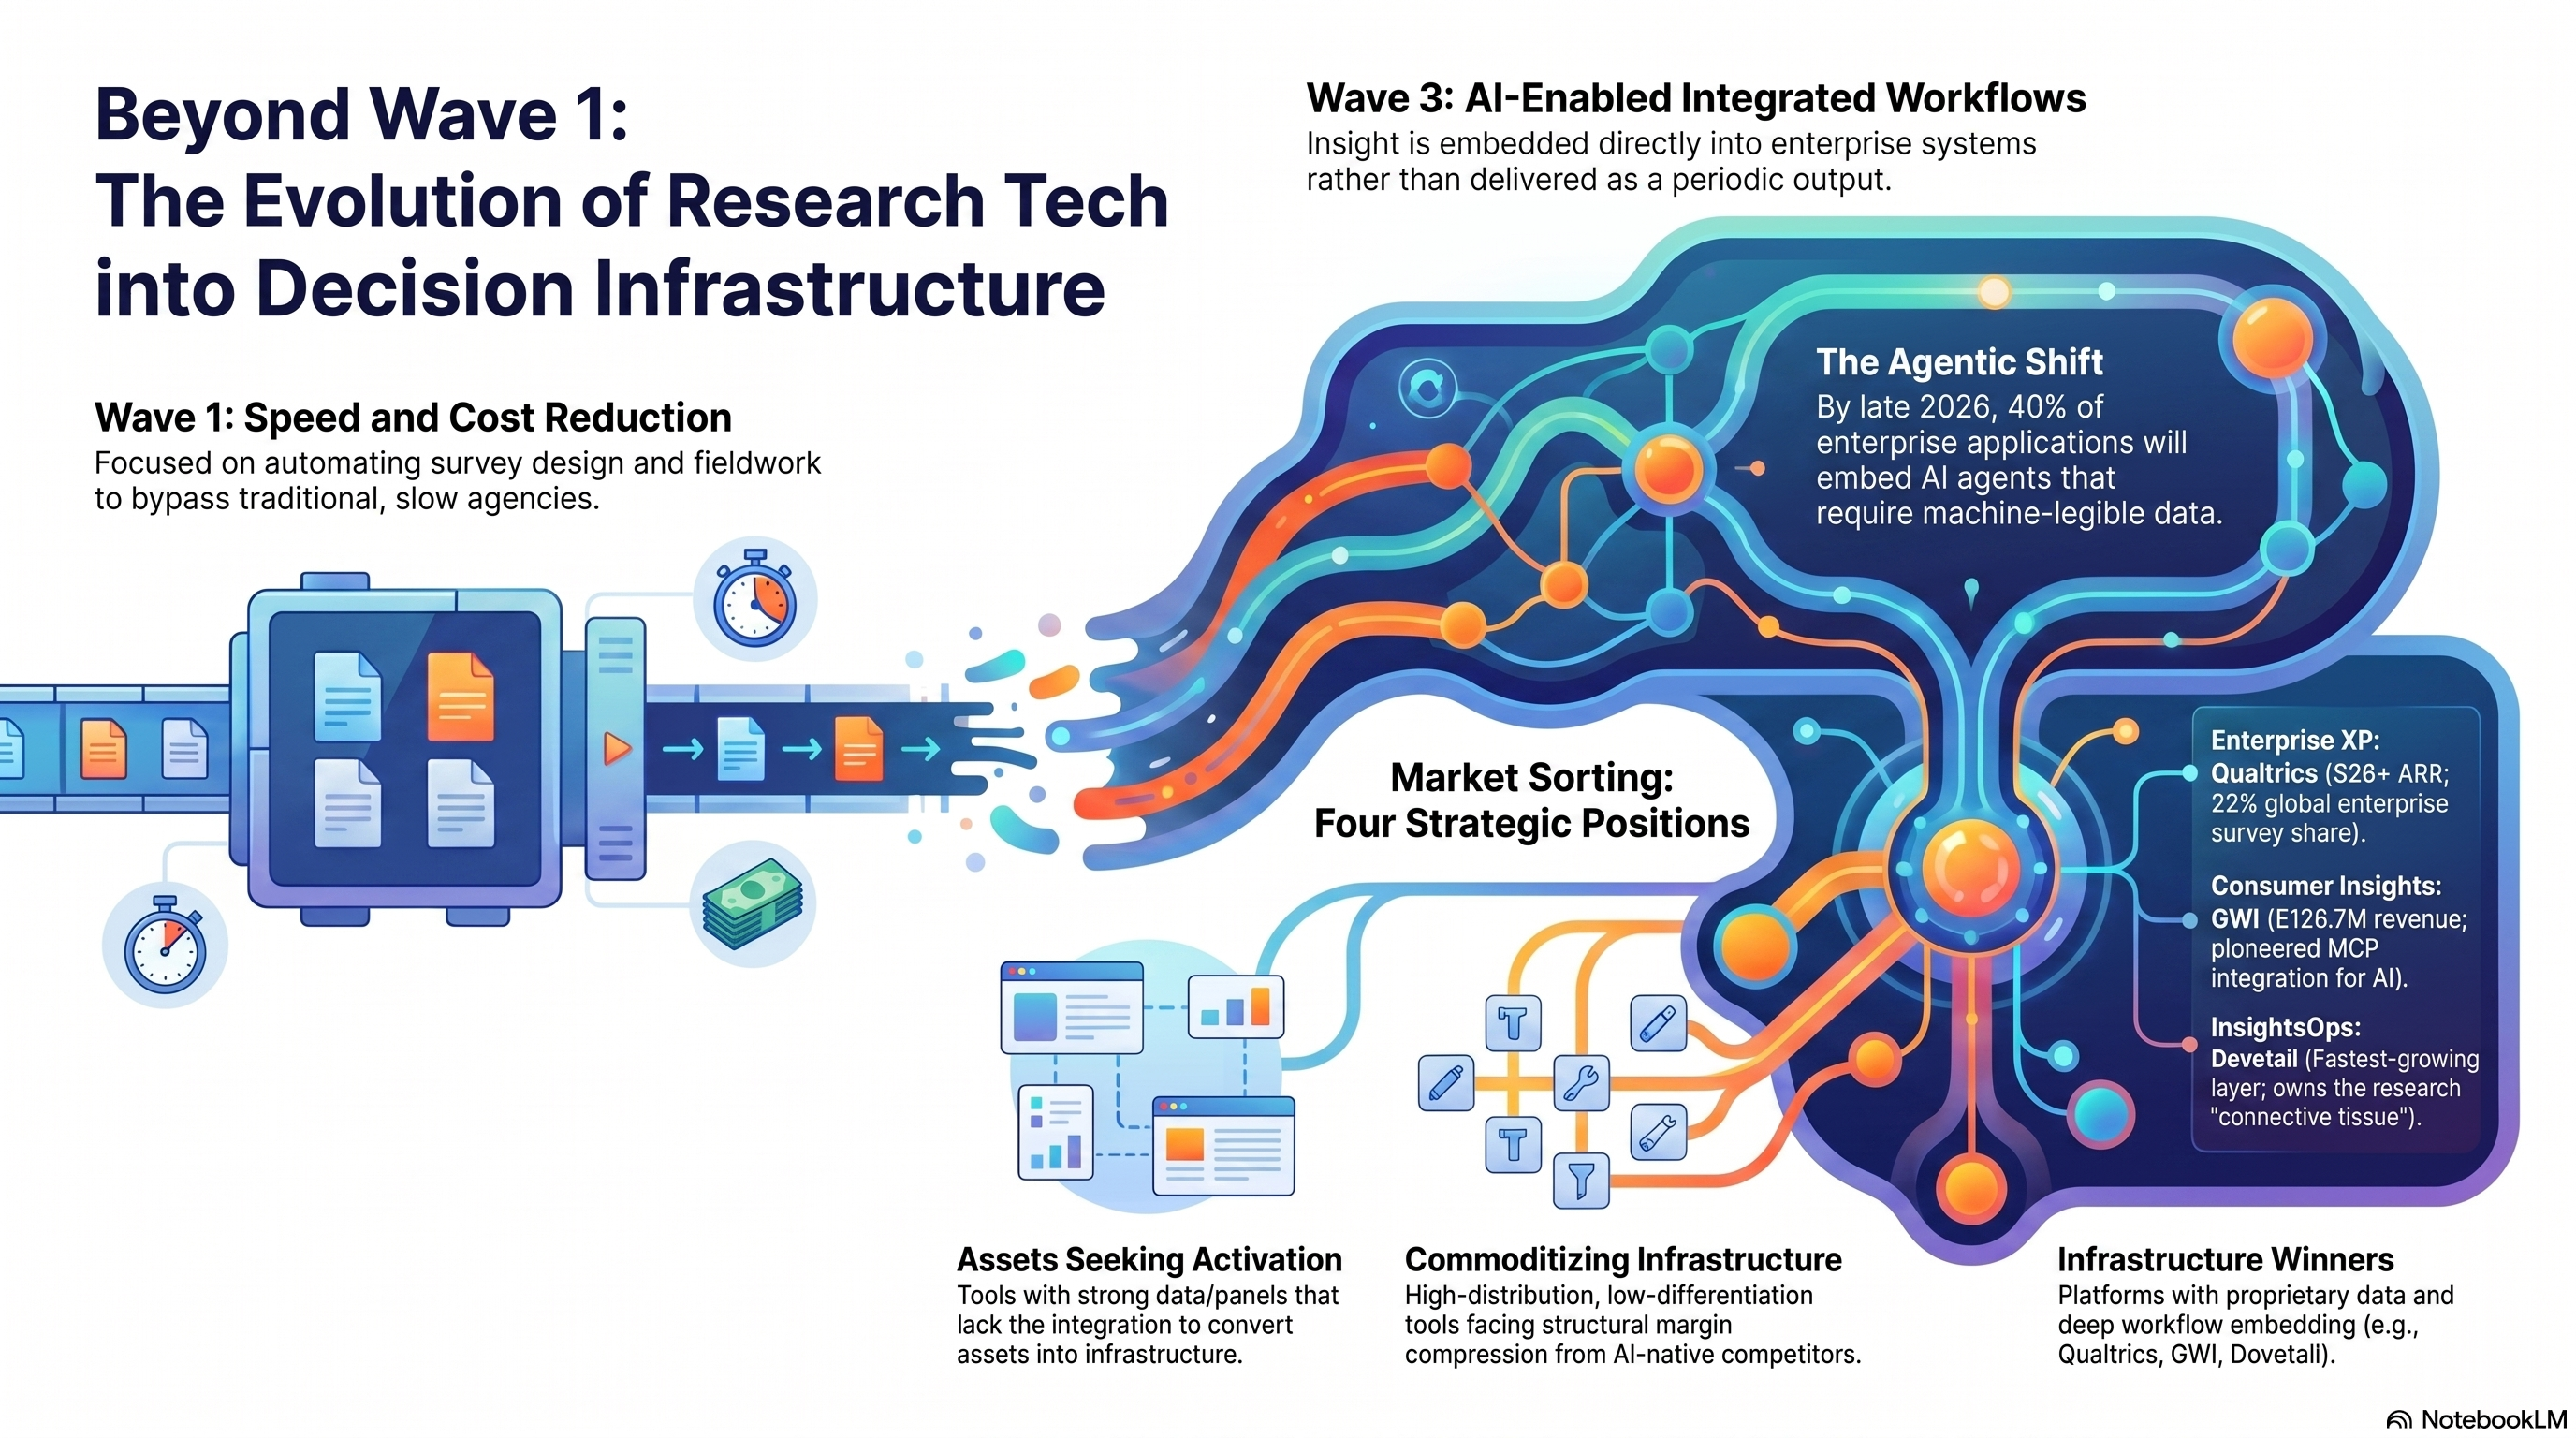
The self-serve market is not a category anymore. It is a capability. The platforms that built their identity around Wave 1 — speed, accessibility, democratized access, cost reduction — are now being sorted by a harder question: did that capability get turned into decision infrastructure, or did it stay as a faster form of the old model? The former compounds. The latter commoditizes. And the market is already sorting.
The core market for self-serve survey and research platforms is approximately $5 billion globally in 2026, growing at 13–15% annually. Expand the aperture to include enterprise experience management platforms and research-grade platforms with meaningful self-serve components, and the addressable market reaches $9–10 billion. That is a real market. But size alone does not tell the strategic story. What matters is which players are inside the decision infrastructure of the enterprise, and which ones are still executing projects outside it.
Note: We’re going to mention a few companies as we dive into this as examples in each category: this is just a representative sampling of players, not a census and no offense is meant to any supplier if you were not mentioned, and no implied endorsement is meant for any we do.
The Wave 1 Win Is Real. The Trap Is Also Real.
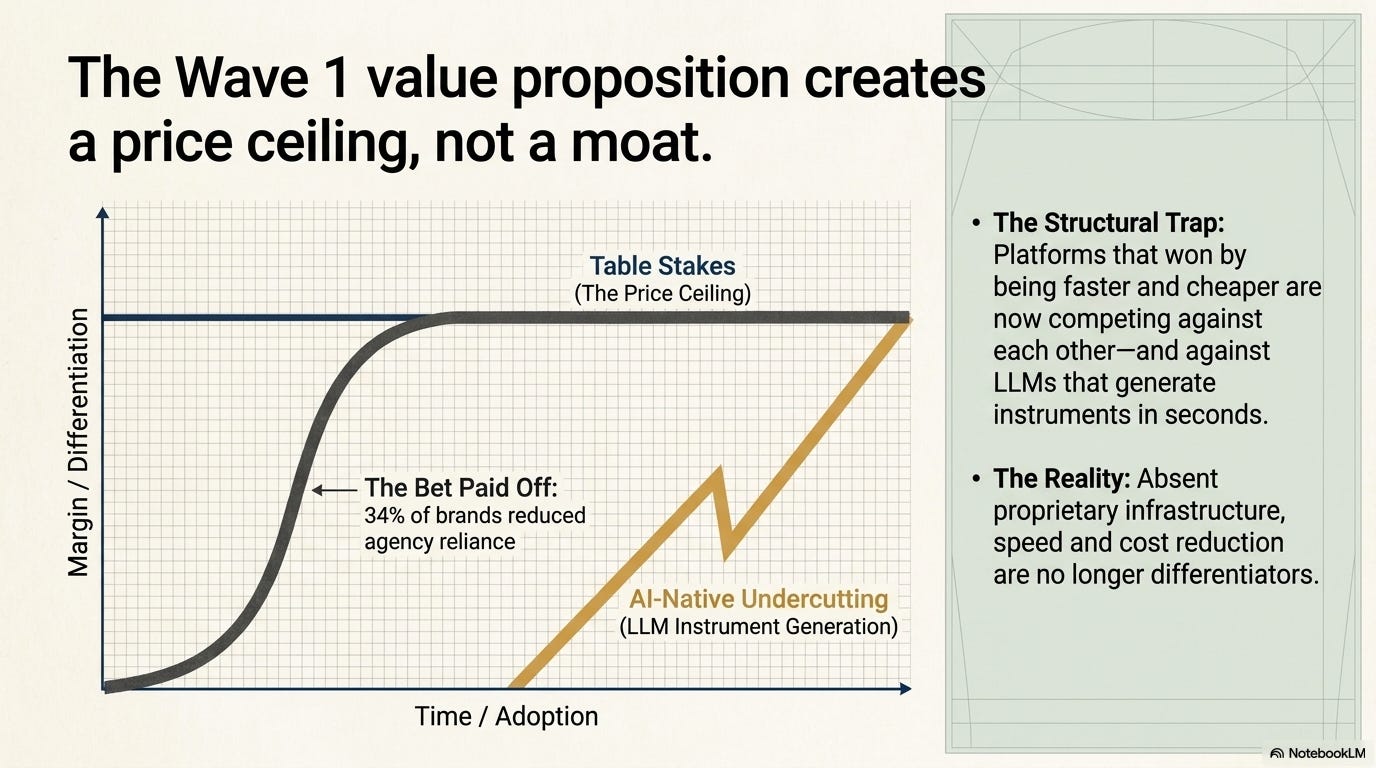
In the Decision Intelligence framework, Wave 1 was Agile, Self-Serve, and Automation — what the market calls ResTech. The pitch was straightforward: take what agencies did slowly and expensively, remove friction, automate the middle, and return control to the brand. It worked. 34% of brands now report that DIY tools are significantly reducing reliance on external research providers, per the GRIT 2026 Insights Practice Report. Brand-side analytics budgets are at all-time highs, with the share of organizations spending above $15 million rising sharply. The spend did not disappear. It moved.
But the trap embedded in that success is structural. Platforms that won by being faster and cheaper than agencies are now competing against each other on the same dimensions — and against a new generation of AI-native tools that can be faster and cheaper still. The Wave 1 value proposition, absent infrastructure, is not a moat. It is a price ceiling.
The deeper issue is Wave 3. Wave 3 is AI-Enabled Integrated Workflow Platforms — the destination the market is moving toward, where insight is embedded directly into enterprise decision systems, not delivered as a periodic output. The self-serve platforms that were the disruptors in Wave 1 are now the incumbents in the path of Wave 3. Most of them are still executing Wave 1. They have added AI features, launched copilot functionality, improved reporting interfaces, and accelerated fieldwork. But adding AI to a self-serve survey platform is not the same as building decision infrastructure. The first is product iteration. The second is category repositioning.
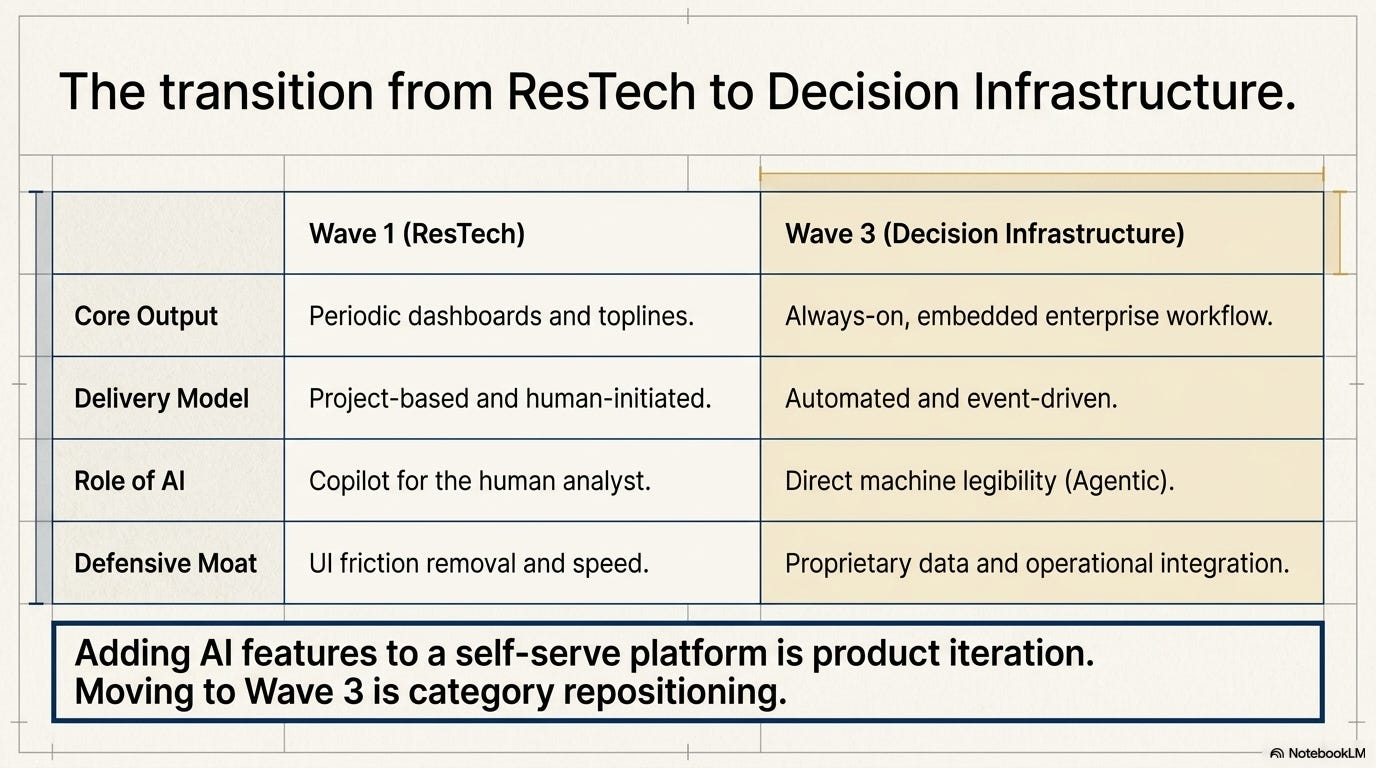
The market is asking which companies have done which.
Six Segments, Two Trajectories
The self-serve and research technology market spans six recognizable segments, and the Wave 1 trap is not distributed evenly across them.
General-purpose survey platforms — SurveyMonkey/Momentive (revenue ~$482M–$750M), Typeform, and a long tail of freemium tools — built the category. They have enormous distribution and brand awareness. But the product has commoditized at both ends: LLMs can now generate surveys in seconds, and enterprise buyers have migrated upmarket to platforms with more infrastructure. The volume here is real. The pricing power is not.
Enterprise experience management — Qualtrics, InMoment, Medallia, Forsta — is the highest-stakes segment. These platforms are embedded deeply in enterprise CX, employee experience, and operational workflows. Qualtrics, taken private by Silver Lake and CPP Investments at $12.5B in March 2023, holds approximately 22% global enterprise survey market share with $2B+ ARR. That embedding is real infrastructure. But it is also the risk: platforms this large have legacy architecture, complex sales cycles, and the organizational inertia that comes with enterprise sprawl. Their activation toward Wave 3 is not optional — it is existential — and it is uneven.
Consumer insights automation — Zappi, Suzy, quantilope, Attest, GWI, Kantar Marketplace — is where the Wave 1 disruption was most concentrated and where the current sorting is most consequential. These platforms bet that consumer insights could be productized, automated, and delivered at brand speed rather than agency speed. Most of the bet was right. Now the question is who built proprietary infrastructure around it. GWI reported revenue of £126.7M in 2025, up 15% year-over-year, and announced MCP (Model Context Protocol) integration in 2026 — the clearest public signal in this segment of a platform actively building toward machine legibility. Suzy sits at approximately $82M ARR with $129M raised, anchored by the Crowdtap panel of 1M+ US members — which is an asset, but only if it is productized as infrastructure rather than accessed as a sample shortcut. quantilope at approximately $42M ARR and $89.4M raised has built one of the stronger normative database foundations in the category, which is the right kind of asset in the right kind of market.
DIY qualitative research — Remesh, Discuss.io, dscout, Voxpopme, AI-moderated entrants — sits at a fork. The specialist platforms with unique methodology, strong client workflow integration, and proprietary analytical capabilities are defensible. The generics that merely digitized the focus group or IDI are not. AI-moderated qualitative is one of the few areas where the technology has genuinely changed what is possible, not just how fast or cheap the old model runs. The platforms that use that capability to deepen the insight product will survive. The ones that use it to cut cost alone will find that every competitor can cut cost the same way.
Agile and rapid insights — Pollfish/Prodege, Upsiide, SightX, Kantar Marketplace — built around speed and accessibility for the long tail of research needs. This segment faces the most acute commoditization pressure because speed and accessibility are table stakes in 2026. Differentiation here requires either proprietary panel infrastructure, specialized normative databases, or deep workflow integration — not just faster turnaround.
InsightsOps and analytics — Dovetail, Stravito, Displayr, Insight7 — is the segment with the highest Wave 3 relevance and the most underappreciated strategic position. Dovetail, Accel-backed and the fastest-growing name in InsightsOps, is not trying to field studies. It is trying to own the connective tissue of the research function — the layer where findings get stored, tagged, synthesized, surfaced, and routed to decisions. That is infrastructure behavior. The InsightsOps layer is the one most likely to compound value as agentic AI scales, because agents need a place to query accumulated human insight, and the platform that owns that repository owns the query.
The Four Strategic Positions
Plot the self-serve and research technology market on two axes — infrastructure depth (the degree to which the platform is embedded in enterprise decision workflows) against data defensibility (the proprietary strength of the underlying data assets) — and the field resolves into four positions.
Infrastructure Winners own both axes. They have proprietary data assets and they are embedded in enterprise workflows, often through integrations that are operationally difficult to replace. Qualtrics (Salesforce and SAP integration depth), GWI (MCP integration, real-time audience intelligence at scale), Dovetail (InsightsOps workflow control), Kantar Marketplace (normative depth plus Kantar ecosystem), and Morning Consult (always-on daily tracking, agentic decision platform economics) sit here. These platforms are being contracted as infrastructure, not purchased as tools.
Assets Seeking Activation have genuine assets — real proprietary data, normative benchmarks, owned panels, or significant client relationships — but have not yet achieved the workflow embedding that converts those assets into infrastructure economics. Zappi has normative databases that are genuinely differentiated but is working through a revenue correction that reflects the limits of Wave 1 positioning. quantilope has strong automated research methodology and one of the better normative foundations in the category. Suzy has Crowdtap, which is a real owned panel asset. InMoment and Forsta have platform depth but face the challenge that every enterprise platform faces: scale creates inertia, and inertia can work for or against you. The distance between “Assets Seeking Activation” and “Infrastructure Winners” is not a data problem. It is a distribution, embedding, and developer-accessibility problem. The companies that close that gap first will compound. The ones that do not will find their assets depreciating as the market moves toward platforms that are already inside the workflow.
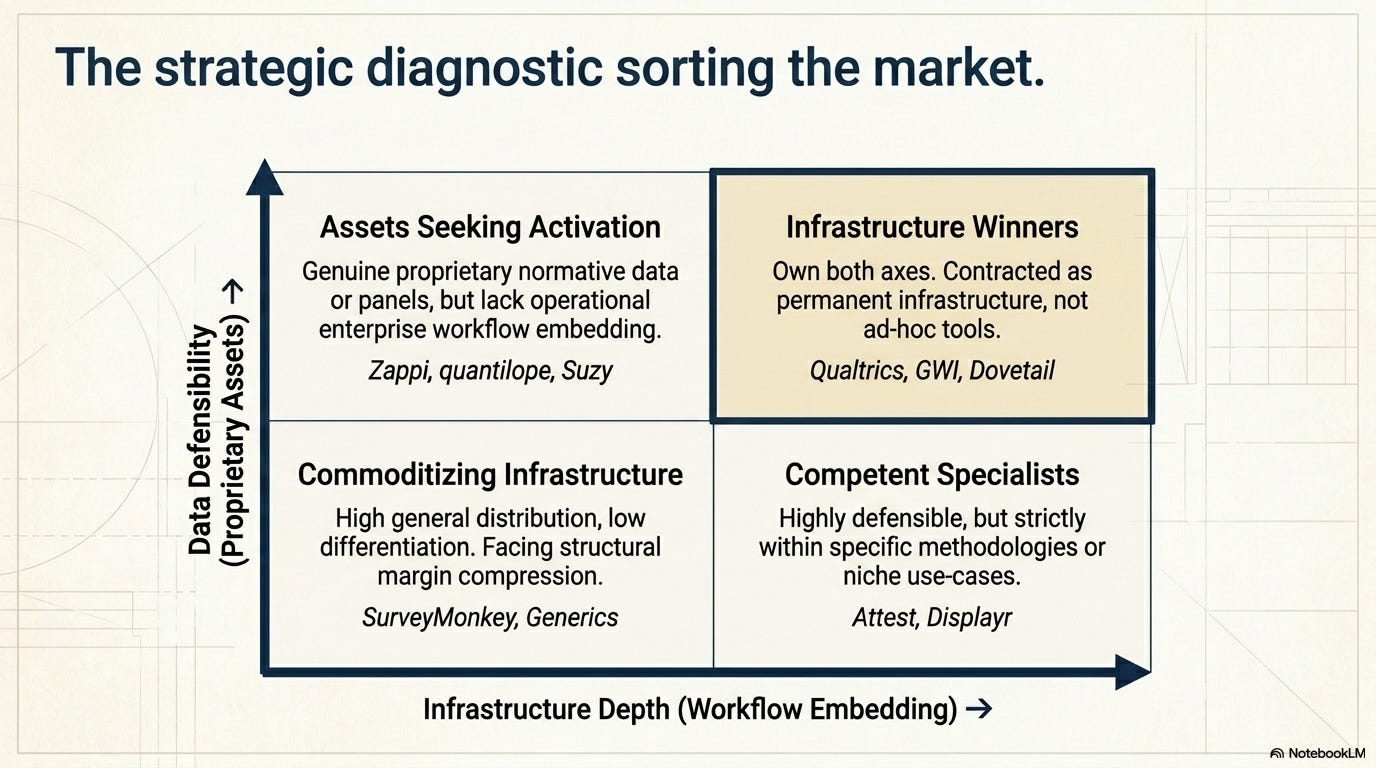
Competent Specialists have built focused, defensible positions in specific segments or methodologies but are not positioned as broad infrastructure. Attest, Displayr, Voxpopme, Upsiide, and Pollfish/Prodege belong here. They do something specific well. Their defensibility depends on staying close to the use case where they are genuinely differentiated, on building the normative data or proprietary analytics that creates switching cost, and on not overextending into general-purpose territory where they have no structural advantage. Specialists who know what they are defending have a viable path. Generalists without infrastructure do not.
Commoditizing Infrastructure is where the competitive logic is brutal. SurveyMonkey/Momentive and the long tail of freemium and generic AI survey builders occupy this position. High distribution, low differentiation, structural margin compression. The path out is either significant upmarket repositioning — which requires assets and capability the current product does not have — or cost leadership in the long tail — which is a fine business, but not a compounding one. This is where Wave 1 success, unextended by infrastructure investment, ends up.
The Agentic Shift Changes Everything
The transition from generative to agentic AI is the single most consequential structural variable in the self-serve market, and most of the platforms in this category have not yet reckoned with what it means.
Gartner projects that 40% of enterprise applications will embed AI agents by end-2026. Agents that operate inside enterprise workflows, make decisions, take actions, and adapt in real time need to access data, design instruments, field studies, and route findings to the systems where decisions are made. In an agentic world, a research platform is either the interface through which agents access human insight — or it is obsolete. That is not hyperbole. It is the architecture of what is being built right now.
GWI’s MCP integration is the clearest public example in this segment of a platform explicitly building toward machine legibility. The Model Context Protocol is not a cosmetic AI feature. It is a structural decision to make the platform queryable by AI agents directly — to position GWI data as something an agent can call on inside an enterprise decision workflow, not something a human researcher retrieves manually and then interprets. That is the difference between being inside the agentic stack and being outside it. Platforms not building agent-compatible APIs are not neutral on this question. They are making a choice to be bypassed.
95% of researchers report using AI tools regularly or experimenting, per the Qualtrics 2026 Market Research Trends Report. That saturation means the AI feature arms race is already over as a differentiator. What is not saturated — and what will determine the next five years — is which platforms have made themselves legible to automated systems, not just useful to human analysts.
Qualtrics has moved in this direction through its partnership with PureSpectrum for synthetic panel integration (August 2025) and through the depth of its Salesforce and SAP workflow embedding. The platform may be slower than the specialist field, but it is structurally difficult to route around when enterprise procurement has already committed to those ecosystems.
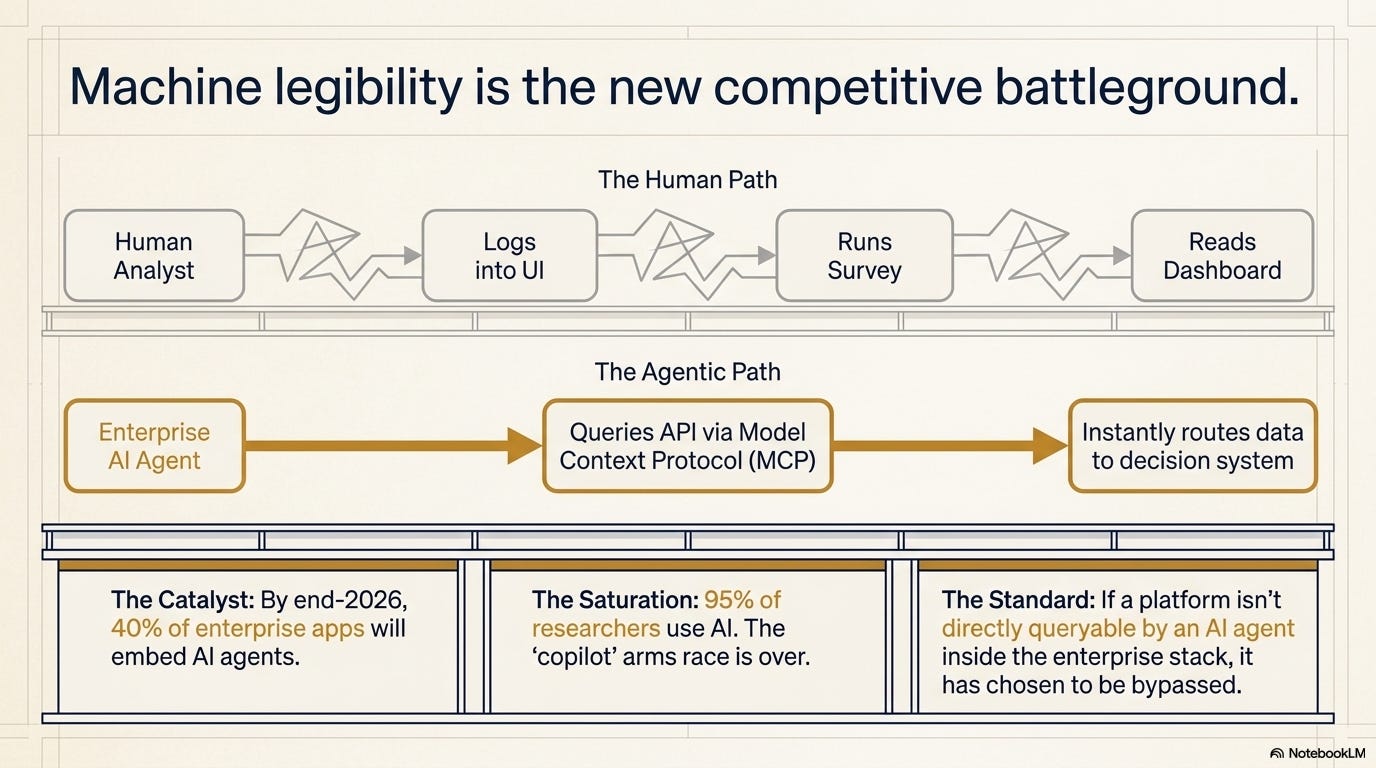
The question the rest of the market has to answer is simpler and harder: when an AI agent inside a brand’s decision system needs to field a study, query a normative database, retrieve audience intelligence, or synthesize prior findings — does it reach for your platform, or does it route around you?
The Five Control Points That Decide the Next Decade
Structural advantage in this market will concentrate around five control points, and most platforms currently hold at most one or two of them.
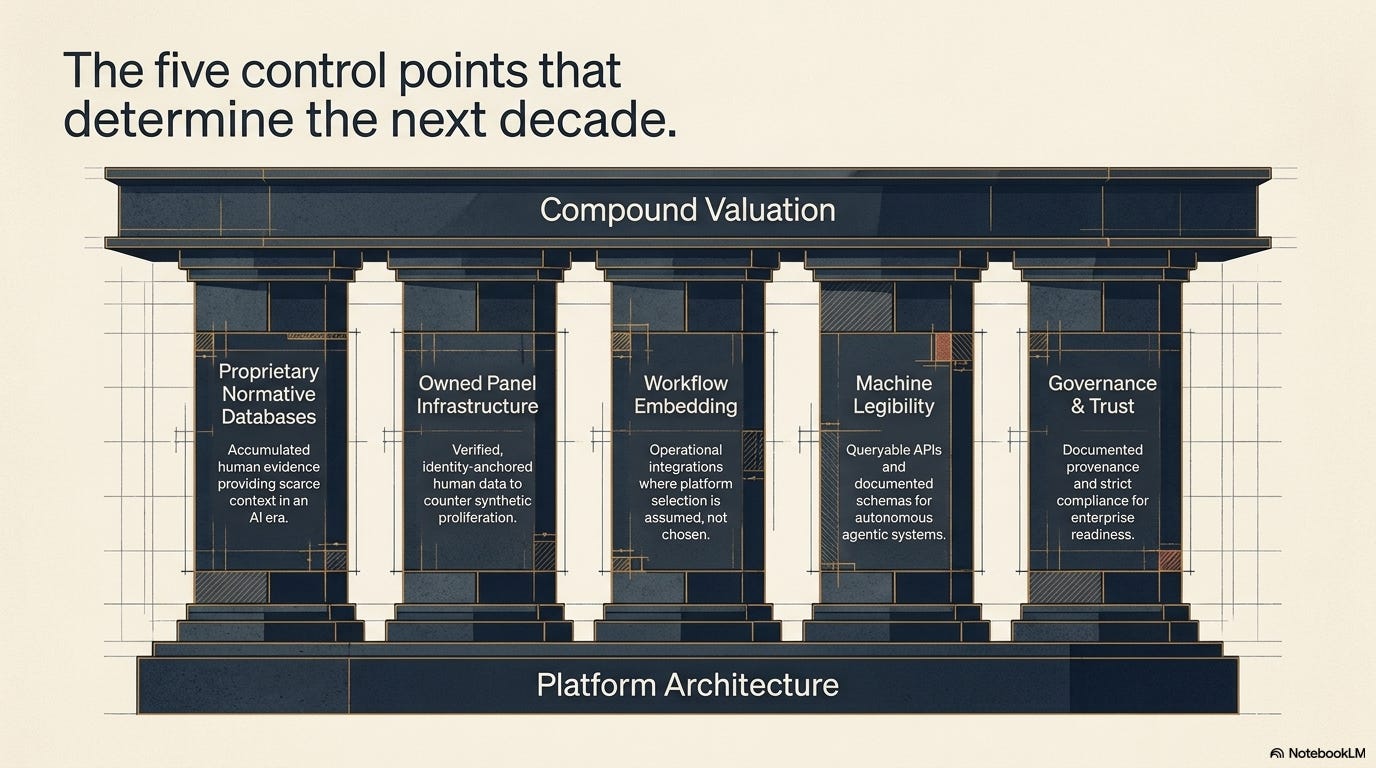
Proprietary normative databases are the most undervalued asset in the category. Zappi, Kantar Marketplace, and quantilope have built genuine normative depth over years of fielding. Those databases represent accumulated human evidence — context that no generic AI can replicate from web priors — and they make the platform structurally more valuable for every study because the client knows what “good” looks like. Normative databases are the original infrastructure play in self-serve research. They are even more valuable in an AI era where context is the scarce input.
Owned panel infrastructure is a separate but related asset. Suzy and its Crowdtap panel, Toluna, Dynata, and GWI hold verified human data assets that are difficult to replicate. In an era of synthetic respondent proliferation and panel fraud acceleration, owned, verified, identity-anchored panel infrastructure is a premium asset — but only if it is productized as such, with provenance documentation, quality controls, and the governance that enterprise AI buyers will increasingly require under frameworks like the EU AI Act.
Workflow embedding — Qualtrics inside Salesforce and SAP, GWI’s MCP architecture, Dovetail inside research operations — is the most durable form of structural advantage in any enterprise software category. A platform inside the workflow is not selected. It is assumed. The battle for workflow embedding is the decisive battle in this market, and most platforms are still fighting for feature adoption rather than operational integration.
Machine legibility for agentic systems is the newest and fastest-growing control point. GWI is the most advanced publicly on this dimension. The platforms that build explicit agentic strategy — queryable APIs, documented data schemas, compatibility with enterprise AI orchestration layers — will be inside the agentic stack. The ones that do not will be accessed only when a human analyst specifically chooses to open them.
Governance and trust infrastructure — EU AI Act compliance, provenance documentation, AI misuse controls, consent architecture — is transitioning from a compliance cost to a competitive advantage. Only 42–44% of brand-side professionals report confidence that their organizations minimize unacceptable AI misuse risks, per GRIT 2026. The platforms that build explicit governance infrastructure — documented provenance, bias assessment, decision-boundary documentation — will not merely satisfy compliance requirements. They will be the platforms that enterprise buyers trust to sit inside high-stakes decision workflows.
The Real Threat Is Not Replacement. It Is Abstraction.
The self-serve market will be tempted to fight the wrong war.
The easy defensive argument runs like this: brands need fast, affordable consumer insight; self-serve platforms deliver it; AI just makes them faster. That argument is not wrong. It is insufficient.
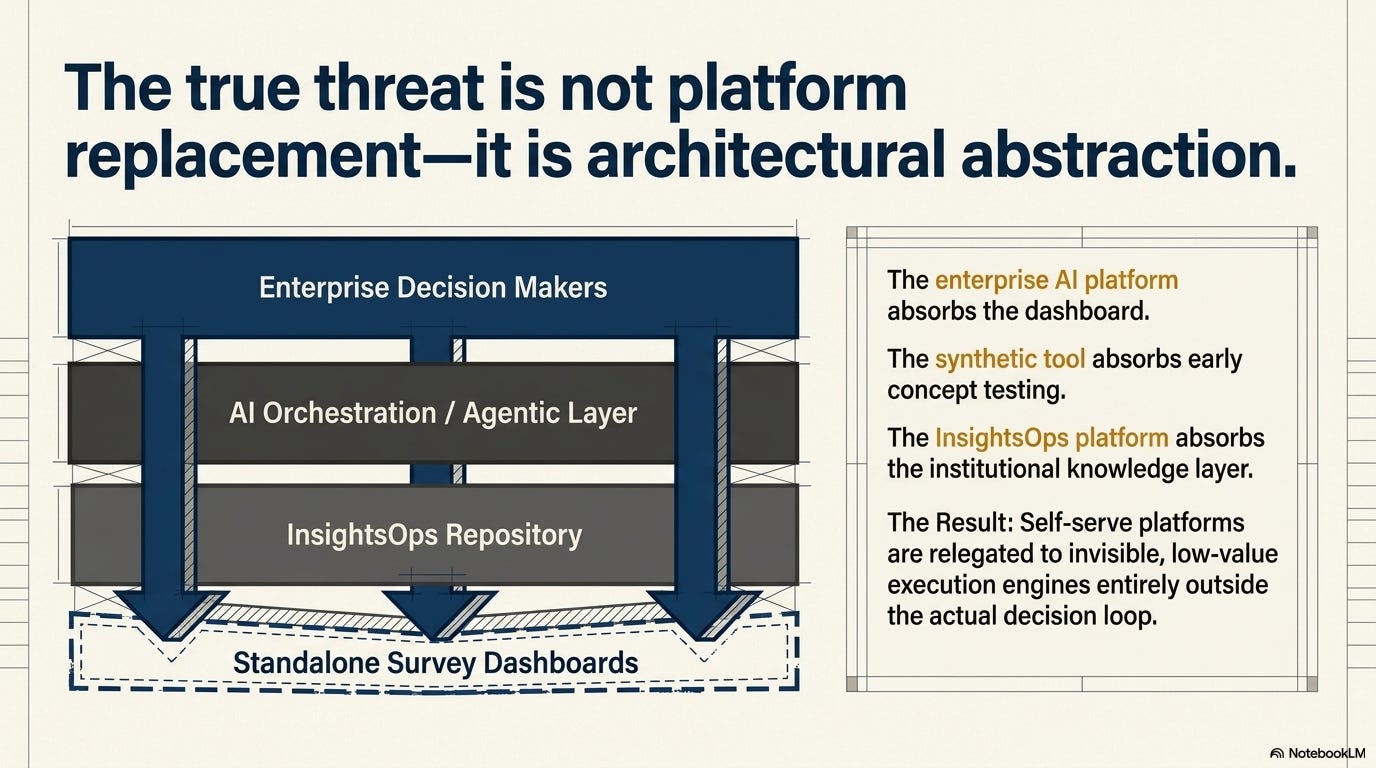
The dangerous scenario is not that self-serve platforms get replaced. It is that they get abstracted out of the decision workflow, one layer at a time. The enterprise AI platform absorbs the dashboard. The synthetic respondent tool absorbs early concept testing. The CX platform absorbs NPS and satisfaction research. The InsightsOps platform absorbs the institutional knowledge layer. The AI agent absorbs the analyst. And the self-serve survey platform, still fielding studies on a project basis, becomes less visible in the decisions that matter — not replaced, but progressively irrelevant to where value is being captured.
That abstraction is already happening in some accounts. Wave 1 platforms that are not actively building toward Wave 3 are experiencing it as a gradual revenue problem that looks like a competitive pricing problem or a macro environment problem. It is neither. It is a structural problem: they are executing the old model at the moment the market is reorganizing around a new one.
The equally bad response is shallow mimicry: launching an “AI-powered” interface on top of a Wave 1 architecture. Every company in this category has done that. None of it changes the structural question. The strategic answer is to activate the assets the industry has already built — normative databases, owned panels, workflow integrations, qualitative expertise, question-performance data, buyer relationships — and convert them into infrastructure. The assets are there. The productization is not.
If self-serve research technology platforms fail to make that conversion, the agentic systems being built inside enterprise AI platforms will define the interfaces, own the query layer, and reduce self-serve platforms to execution vendors. That is not a threat from a competitor. That is abstraction from inside the client’s own infrastructure.
What This Means for Buyers, Suppliers, and Investors
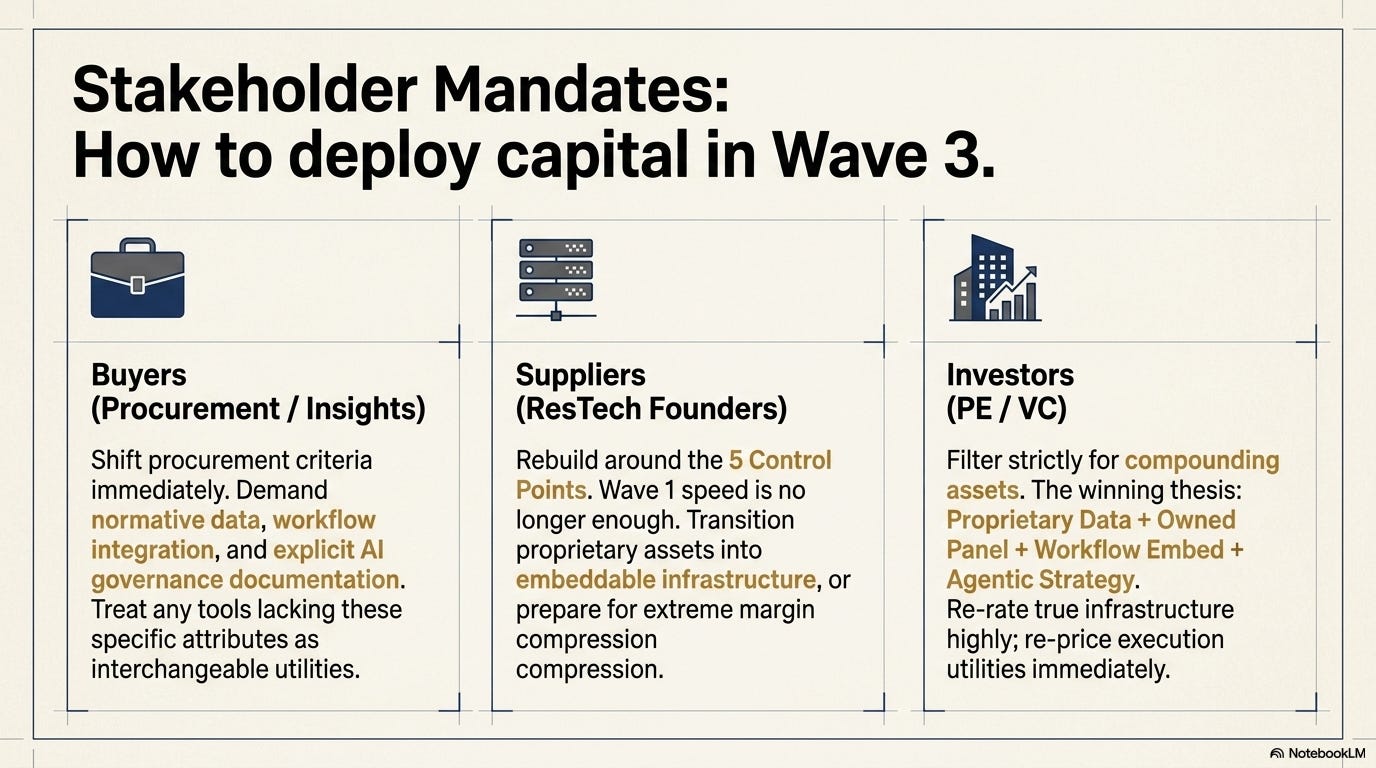
For buyers, the self-serve market now requires a more discriminating procurement posture than “which platform is fastest and cheapest.” The relevant questions are structural: which platforms are embedded in your existing enterprise workflow, and which require a parallel decision to retrieve? Which have normative databases relevant to your category and decision types? Which are building agent-compatible infrastructure that will still be useful when AI agents are doing the routine fielding and synthesis? And — critically — which have the governance documentation to satisfy the AI oversight requirements your legal and compliance teams will eventually enforce? The platforms that answer those questions well are assets. The ones that cannot should be treated as utilities — useful, interchangeable, and priced accordingly.
For suppliers, the mandate is a forced choice about identity. Self-serve is a capability. The question is what that capability is in service of. The platforms that have built normative depth, owned panels, workflow integration, and are actively building agentic compatibility are on the right trajectory, even if the execution is incomplete. The platforms that are still leading with speed and cost reduction as their primary value proposition are in the wrong decade. Wave 1 won. The next wave is not going to be won by doing Wave 1 faster. It will be won by the platforms that have turned Wave 1 capability into Wave 3 infrastructure — by embedding, by activation, by governance, and by building the machine legibility that agentic AI demands.
For investors, the filter is sharper than “self-serve research technology is growing at 13–15% and AI is a tailwind.” The segment will grow. The question is who compounds inside that growth and who gets compressed. The investment thesis that holds is: proprietary normative data plus owned panel infrastructure plus workflow embedding plus explicit agentic strategy. Platforms with one or two of those elements are interesting. Platforms with three or four are compounding. The revenue correction at Zappi and the divergent growth trajectories across this category are not noise. They are the early signal of the structural sort the market has already begun. The assets that convert into infrastructure will re-rate. The ones that do not will reprice toward utility-level multiples. The window to build the control points is open. It is not open indefinitely.
Insight Innovation Ventures invests in AI and analytics startups across the USA and UK, with a focus on data infrastructure, research technology, and AI-native insight platforms. This post is part of an ongoing series on the structural transformation of the insights and analytics industry.